LATEST INSIGHTS

Tasman Capital Partners Fund IV reaches first close and completes initial investments
Company News
08 September 2026
Technical
19 December 2023

Annex IV reporting for funds registered for marketing in Europe

This is a reminder that AIFMD Annex IV submissions for the period ending 31 December 2023 are due to be filed by 31 January 2024. The requirement to report is in place for:

All EU AIFMs, UK AIFMs and non-EU AIFMs which:
  1. Have active funds with commitments from EU/UK LPs marketed to under AIFMD; and
  2. Have AIFs currently being marketed under AIFMD in the EU / UK.

We have seen a marked year on year increase in GPs seeking European capital, and expect this to be the busiest filing period of the last decade. With many GPs planning to return to fundraising in 2024, we have also seen a large number of managers seeking to tidy-up any outstanding historic submissions, which may have been missed in the past.

There is no harmonised system for completing and filing these reports across the EU, rather each regulator has its own reporting portal with various nuances in reporting format and process. This reporting burden often falls to fund finance or compliance teams who may be unfamiliar with the reporting process, which will be required for all AIFs by 31st January 2024, and potentially as often as quarterly thereafter depending on the requirements.

Langham Hall has been completing Annex IV reporting for AIFMs and AIFs since 2014. We prepare and file hundreds of Annex IV reports each year and are familiar with the reporting portals across all jurisdictions. Langham Hall is able to set up the portal access for each country, and complete and file these Annex IV reports in the relevant formats required by each regulator. We file these reports directly with the regulator with minimal involvement required from the fund manager.

Company News
12 December 2023

Langham Hall supports Farview Equity Partners’ deal flow

Farview Equity Partners (‘Farview’), the Europe focused growth investor, continues to deploy capital and now has four deal structures in a range of financial and ESG focused businesses. This includes investments in Evora Global, Unily, Exclaimer and Amplience.

Langham Hall has been appointed to provide administration and accounting services to the deal structures from our Guernsey office, which assisted Farview in transitioning structures from another administrator in 2022.

Guy Sochovsky, founder and partner at Farview said ”Langham Hall has been a valuable partner to us as we continue to execute our investment strategy in Europe. Their communication, responsiveness and ability to problem solve is second to none.”

We look forward to working with Farview as they continue to execute this strategy.

About Farview Equity Partners

Farview Equity Partners invests in growth-oriented enterprise and financial technology companies in Europe. Founded in 2019 by a team of highly experienced professionals with sector-specific growth equity, operational and legal backgrounds, our mission is to empower European enterprise and financial technology companies to grow beyond their current horizons.

Technical
8 November 2023

ACSP after Royal Assent: What you need to know

The Economic Crime and Corporate Transparency Bill 2022 was passed into law on 26 October 2023 and became The Economic Crime and Corporate Transparency Act 2023(the “Act”).

The Act is designed (amongst other things) to tackle money laundering and strengthen the UKs company registrar, known as Companies House. It will reform the role of Companies House radically, turning it into an active gatekeeper.

As anticipated, as part of these changes the Act introduces an identity verification requirement for:

  • all new and existing company directors,
  • People with Significant Control (PSC), and
  • those delivering documents to Companies House UK.

Filing requirements for limited partnerships and limited liability partnerships have also been reformed under the Act, with part of that reform being that partners will also require verification at Companies House.

To help facilitate verification, the Act introduces the new role of the Authorised Corporate Service Provider (‘ACSP’).

There will be a transition period for existing directors and their equivalents, and for PSCs to verify their identity in. This transition period will provide existing directors and PSCs time to comply with the new requirements, whilst ensuring the integrity of data already on the register. Detailed guidance should be issued shortly.

How can Langham Hall help?

Building on our success as one of the top ten verification agents in the country for the Register of Overseas Entities, Langham Hall will be acting as an ACSP and will be able to assist clients with fulfilling these new verification requirements.

If you wish to discuss the requirements and how Langham Hall can assist you please do not hesitate to get in contact: LHACSPServices@langhamhall.com

Technical
18 October 2023

Authorised Corporate Service Provider: What you need to know ahead of Royal Assent

The Economic Crime and Corporate Transparency Bill 2022 (‘the Bill’) is upcoming legislation designed to tackle money laundering and strengthen the UKs company registrar, known as Companies House. This is a follow on from the Economic Crime Transparency and Enforcement Act 2022, which saw the implementation of the Register of Overseas Entities for those entities holding UK land or property.

The Bill is expected to introduce an identity verification requirement for:

  • all new and existing company directors,
  • People with Significant Control, and
  • those delivering documents to Companies House UK.

Filing requirements for limited partnerships and limited liability partnerships will also be reformed under the Bill, with part of that reform being that partners will also require verification at Companies House.

To help facilitate verification, the Bill will introduce the new role of the Authorised Corporate Service Provider (‘ACSP’).

Building on our success as one of the top ten verification agents in the country for the Register of Overseas Entities,

Langham Hall intends to become an ACSP and will be able to assist clients with fulfilling these new verification requirement.

The Bill is expected to receive Royal Assent within the next month and detailed guidance should be issued shortly after that.

If you wish to discuss the requirements and how Langham Hall can assist you please do not hesitate to get in contact: LHACSPServices@langhamhall.com

ACSP after Royal Assent: What you need to know

Technical
11 October 2023

Marketing of GP-led continuation funds in Europe

The last few years have seen a significant rise in the number of GP-led continuation funds being launched, with the market growing from just $5 billion in 2013 to around $50 billion in 2022. Continuation funds allow existing investors to access liquidity and rebalance or de-risk portfolios, while giving new or rolling investors access to mature, pre-identified companies with a shorter holding period than a primary fund. For the GP, a continuation fund allows the manager to potentially realise higher returns as market conditions improve, whilst continuing to hold strong performing assets and crystalising carry.

Establishing these funds comes with some unique challenges, such as price setting against valuation, conflict management and also LP diligence on the asset or portfolio. Another question we are increasingly getting asked is whether a continuation fund marketed in Europe is classified as an AIF under the AIFMD (‘Alternative Investment Fund Managers Directive’).

The European Securities and Markets Authority defines an AIF as “a collective investment undertaking… that raises capital from a number of investors, with a view to investing it in accordance with a defined investment policy for the benefit of those investors.” In the case of continuation funds, these are often widely marketed by either the manager, or an appropriate agent. Regardless of the existence of a pre-identified portfolio, the activity of marketing to multiple investors and continuance of management in accordance to a defined investment objective means that in our view, a proposed continuation fund would fall under the definition of an AIF where marketing in Europe is concerned.

Implications of marketing an AIF

If defined as an AIF, then a proposed continuation fund marketed in Europe will need to comply with the AIFMD. In practice, this means a continuation fund can be;

a) Pre-marketed in all EU27 – since the harmonisation of pre-marketing rules in August 2021, pre-marketing can be undertaken by a regulated AIFM or MiFID entity in all EU member states, providing a pre-marketing notification is filed with the home regulator within 14 days of the commencement of pre-marketing. Non-EU sponsors are able to engage a regulated AIFM to file this notification, and indeed we have seen a number of North American sponsors doing this. In the case of pre-marketing, only draft documents (excluding subscription documents) may be shared with potential investors.

AND

b) Registered under the NPPRs in the countries in which it is marketed – after any period of pre-marketing (if undertaken), it is possible to undertake formal marketing by way of a country-by-country registration. It is important to note that this is not possible in much of Southern Europe, and countries including Germany and Denmark require a depositary-lite to be named on the registration.

OR

c) Set up as an EU standalone fund – if set up in an EU member state such as Luxembourg or Ireland, a continuation fund can be formally marketed to all EU27 under the marketing passport. Setting up an EU fund would require an AIFM and a Depositary to be appointed.

In practice, we have seen recently a number of non-EU sponsors engaging a host AIFM (such as Langham Hall) to act as AIFM for the period of pre-marketing. Once the manager has further clarity on the location of interested LPs, then an informed decision can be made on whether to register a non-EU fund on a country-by-country basis, or set up an EU vehicle.

Who is undertaking marketing?

One important consideration in the marketing of continuation funds is who will actually be undertaking the activity of marketing. Although the regulations mentioned above allow for the proposed fund to be marketed, many countries also require the distributor to be appropriately regulated. In our experience, either;

  1. The sponsor undertakes the activity of marketing themselves, and is regulated to do so in Europe or is “chaperoned” by a regulated AIFM/MiFID entity; or
  2. The sponsor appoints a placement agent that is appropriately regulated to distribute products in Europe

Again in practice, many non-EU sponsors will engage specialist secondaries focused placement agents who themselves should be appropriately regulated in Europe, but this is an important consideration.

What next?

For sponsors considering launching a continuation fund, it is important to consider the regulatory implications before going to market. We expect the GP-led market to continue to grow, particularly as LPs continue to allocate capital to these opportunities. We are working with a number of sponsors to help them navigate the European regulatory environment, assisting with both pre-marketing, but also later formal registration either via the NPPRs or the EU passport. Please do get in touch if you would like to discuss further.

Life at Langham Hall
25 September 2023

Langham Hall charity initiatives 2023

Langham Hall is committed to giving back to the communities in which it operates. We champion our staff to be involved in a variety of activities to widen their life experiences and perspectives.

Our global offices have undertaken a wide range of charity and fundraising activities over the past six months, ranging from white collar boxing to career coaching in local schools.

Check out what our teams have been up to:

Jersey

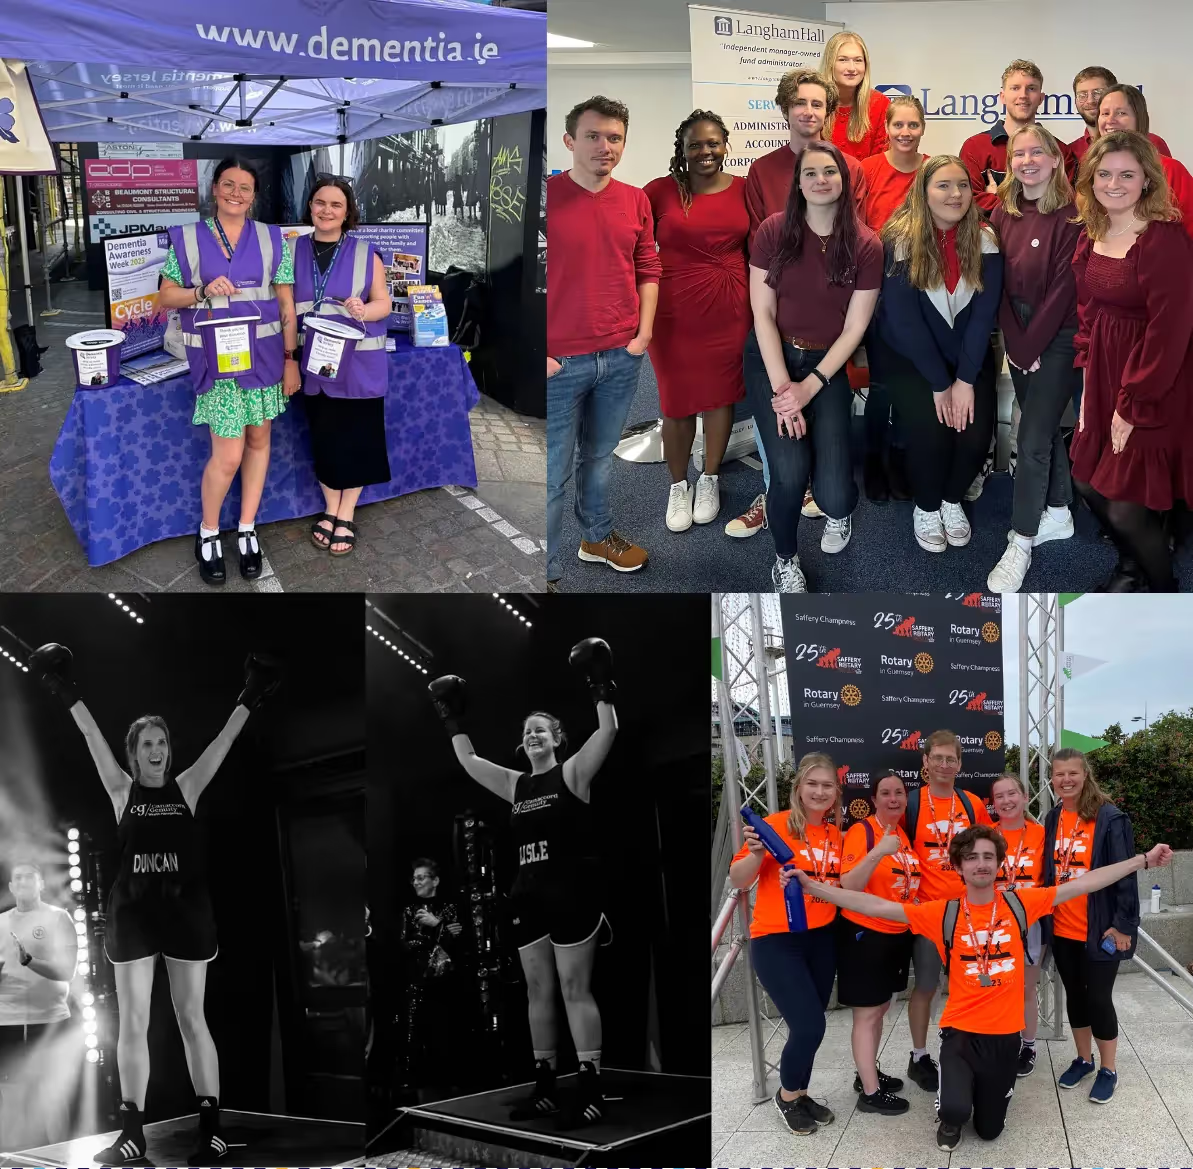
This year, the Jersey office has partnered with two local charities, Jersey Hospice Care and Dementia Jersey. To raise well needed funds, they have taken part in a variety of initiatives in the last few months including raising money for Dementia Jersey by manning their stall in town and donating their monthly collections to both Dementia Jersey and Jersey Hospice Care.

Guernsey

The Guernsey office selected Guernsey Alzheimer’s Association as their chosen charity of the year and have since taken part in a variety of initiatives to support the charity with fundraising and volunteering. This included taking part in the annual Guernsey Alzheimers’ Golf Day with former professional rugby player Kyran Bracken. During early June staff took part in “The Saffery Rotary Walk,” which saw them go around the island in a 39-mile walk. The initiative raised money for 25 local charities including the Priaulx Premature Baby Foundation, GSPCA and Les Bourgs Hospice.

USA

For the first half of the year, the USA office partnered with the Association to Benefit Children (‘ABC’). ABC provides early childhood education and early intervention programs for children aged 0-5, providing a nurturing foundation to children from New York City’s most vulnerable families. The team collected hundreds of books which were presented to the charity during an engagement day with the students. The Langham Hall team took part in classroom activities and presentations.

Luxembourg

The Luxembourg office has been focusing their efforts on humanitarian aid for the Turkey-Syria Earthquake Appeal. Through direct transfers, employees generously contributed to AHBAP and OXFAM. Langham Hall Luxembourg matched their donations with an equal contribution to further support employees’ commitments. In addition to monetary support, the team collected clothing and different essential items delivered to the Embassy of Turkey.

UK

The UK office has this year renewed its partnership with Future Frontiers, an award-winning education charity that exists to ensure young people fulfil their potential at school and when transitioning to education, employment or training at age 16. The initiative saw young people attend a 4-week programme of face-to-face coaching delivered by a team of 10 volunteers from our London office. The office also matched employee contributions for the Turkey and Syria DEC Appeal as well as made donations to the employee’s quarterly chosen charities CALM, Shelter and Dog’s Trust.

We also encourage our staff across all jurisdictions to take on their own challenges and initiatives.

  • Kiera Lisle from Jersey arranged a 15 mile walk in aid of Brighter Futures Jersey
  • Kiera Lisle and Tara Duncan from Jersey took part in the Jersey White Collar Boxing raising funds for Brighter Futures Jersey and Jersey Hospice Care
  • Members of the UK office took part in several charity runs and marathons

We look forward to continuing all our global charity initiatives during the second half of 2023.

We are proud to stand together and extend a helping hand to those in need.
Company News
20 June 2023

Langham Hall celebrating ten years of operations in Luxembourg

Langham Hall is delighted to be celebrating ten years of operations in Luxembourg.

Partner and Head of Luxembourg, Keith McShea, joined Langham Hall in 2013 to establish the services of Central Administration and Depositary to Real Estate, Private Equity, Debt and Infrastructure funds. In 2018, Langham Hall obtained its AIFM licence in Luxembourg, with AIFM services under the management of Hanny Tirta, who is Partner and Head of Regulatory Hosting (UK and Luxembourg). The Luxembourg team has organically grown since 2013 from a handful of staff to over 200 employees covering all of Langham Hall’s service lines.

Over the last ten years, Luxembourg has grown exponentially as a domicile for alternative funds and the gateway to European investors, and the regulatory landscape remains ever-changing. Langham Hall Luxembourg has built up a strong fund client base over this time, providing the full range of Central Administration, Depositary and AIFM services to alternative funds across the range of illiquid asset classes.

Keith McShea said: “Thanks to our employees’ effort and commitment, and the support of our clients, we have been able to grow into a market leader in Luxembourg in the servicing of private equity, real estate, infrastructure, and debt funds.”

Hanny Tirta added: “We have developed a formidable reputation in the Luxembourg market by sticking to our corporate mission to be the most professional provider of administration and AIFMD services.”

Managing Partner, Rob Short added: “Congratulations to the management team and staff for growing a business of this size and quality in Luxembourg. Thanks also to our clients for their support during this period. We look forward to deepening these relationships and forging new ones.”

To mark the occasion, Langham Hall invited clients and industry associates to celebrate this key milestone.

__wf_reserved_inherit
Technical
18 May 2023

Anti-money laundering or data protection: What takes precedence?

It is estimated that up to $2 trillion is laundered every year, almost 5% of global GDP. To combat this, the implementation of anti-money laundering (‘AML’) laws has aimed to increased transparency within financial services, but this creates an inherent conflict with data privacy laws, such as the EU’s General Data Protection Regulation (‘GDPR’). This conflict was the subject of a recent judgement by the European Court of Justice (‘ECJ’) in November 2022.

In the Joined Cases C-37/20 – Luxembourg Business Registers, and C-601/20, the ECJ ruled that access by the general public to beneficial ownership information of companies incorporated in the European Union, as prescribed by article 30(5)(c) of the 5th EU Anti-Money Laundering Directive (2018/843) is invalid.  Further, the ECJ ruled that Luxembourg’s facilitation of general public access to information on beneficial ownership of Luxembourg entities following Luxembourg’s implementation of the 4th EU AML Directive (2015/849), is invalid.

The ECJ ruled that public access to information on beneficial ownership constituted a serious interference with the fundamental rights to respect for private life and to the protection of personal data.

The judgment served to highlight the inherent conflict between:

  1. beneficial ownership disclosures that assist in combating anti-money laundering and terrorist financing (i.e. establishing who sits behind a company or other structure); and
  2. the protection of individuals’ personal data.

In short, it is necessary to compromise on one set of laws to properly implement the other.

The privacy versus transparency debate

Both transparency and privacy are incredibly important.  But the new judgment reignites the debate about which should take precedence. Individual personal data has for too long been used freely and with utter disregard to any adverse consequences, by governments and corporates, often for selfish commercial purposes. Recent technological advancements and the exponential growth in the use and influence of social media means that it is critical to limit the use of personal data to manage our right to privacy and safety.

The EU General Data Protection Regulation (2016/679) came into effect in May 2018 with the aim of protecting EU citizens by giving individuals control over their personal data, including the right to access, correct, and delete it. The GDPR has helped deter governments and corporates from using and abusing personal data without regard for the rights of individuals.

The continued efforts of the Financial Action Task Force and the EU, among others (notwithstanding the leading nations’ double-standards on the use of sanctions and enforcement of AML laws), have undoubtedly helped restrict some financial crime. Scandals such as “The Panama Papers” and offshore data leaks created momentum towards complete transparency.  Nevertheless, money laundering and terrorist financing remains endemic across the global economy, including in onshore and offshore finance centres to varying degrees.

The drive to fight money laundering

The identification of beneficial owners of structures and investments is fundamental to combatting anti-money laundering. The EU largely took the lead with the implementation of beneficial ownership registers disclosing an individuals’ name, date and place of birth, country of residence and interest in a company. Luxembourg was a leader in allowing such data to be publicly accessible. (It should be noted that Luxembourg AML laws did already allow public access to beneficial ownership information to be restricted in the event of security risk on a limited case-by-case basis.) Such public access to personal data has undoubtedly deterred some money launderers from investing in the EU.

However, public access to the beneficial ownership of EU companies undoubtedly cuts across GDPR and arguably brings unwanted and unfair attention to numerous law-abiding individuals and families.

We believe it is perfectly possible to implement and enforce strong rules for both initiatives that clearly manage the inherent conflicts.

To start, supranational and national authorities should explicitly take into account the inherent conflicts between transparency and privacy when reviewing and updating relevant rules. For example, which takes priority and when? Such an approach would be preferable to relying on the courts to determine precedence. This will help ensure that everyone, including players in the European financial services industry, can apply clear and consistent rules and avoid future confusion.

There are also practical ways that these conflicts could be better managed, including the use of secure data-sharing platforms and standardised reporting templates at a national level for regulated financial services providers.

Langham Hall has policies and practices to comply with both sets of laws and manage the conflicts to ensure compliance with both. Staff members are trained on risks related to both the fight against money laundering and the protection of personal data. Our systems are built to appropriately protect information gathered during our due diligence process.

From a contractual perspective, investor and client consents in relation to sharing personal data in order to comply with AML rules are typically contained in client contracts or fund subscription agreements. It is these provisions that often facilitate Langham Hall and other financial services businesses sharing of personal data between other regulated counterparties, but only where it is strictly necessary to do so in order to comply with AML rules.

Technical
27 April 2023

Conference season: What constitutes pre-marketing?

Conference season is back in in full swing, with many of the flagship events returning to entirely in-person attendance. Indeed, it feels almost back to the pre-Covid era, but some things have moved on.

So what’s new? Pre-marketing a fund in the EU (since 2nd August 2021) now requires a filing notification. Fund sponsors attending conferences in the EU should seek legal advice initially to scope out whether their proposed activities during and after conference attendance constitute pre-marketing. There is also increased scrutiny from EU regulators, not least because of Brexit (which officially took effect on 31st January 2020) to ensure that the rules and regulations for access to the EU market are being adhered to.

Am I pre-marketing by attending a conference in the EU?

Attendance per se, does not necessarily mean you are undertaking pre-marketing activities in the EU. However, what you do during the conference and/or post conference may bring such activities under the definition of “pre-marketing”.

Under the new Cross Border Distribution Directive (‘CBDD’), pre-marketing is defined as:

  1. the provision of information or communication, direct or indirect, on investment strategies or investment ideas;
  2. by an EU AIFM or on its behalf (e.g. by a placement agent);
  3. to potential professional investors domiciled or with a registered office in the EU;
    in order to test their interest in an alternative investment fund (an ‘AIF’), which is not yet established or established but not yet notified for marketing under Directive 2011/61/EU (the ‘AIFMD’); and
  4. which does not amount to an offer to invest in the relevant AIF.

The legislation is relatively new, therefore there may be situations where it is arguable whether or not you are pre-marketing. However, if you (or your placement agent) are sharing materials with fund specific details (in draft) at the conference where you are looking for potential interest to invest, this will likely fall within the definition of pre-marketing. In our experience, the materials/information shared during pre-marketing can range from a couple of pages of draft heads of terms, to draft LPA/PPMs in a data room with due diligence materials on the fund sponsor. There is no prescriptive list of what must be shared in pre-marketing and legal advice should be sought that what is shared is allowed under CBDD. What definitively is not allowed under the CBDD is any final documents relating to the fund or a subscription document/application form for interest (in draft or in final form).

The conference itself is only part of the potential scope of activities that may fall under the CBDD, as any subsequent communication thereafter arising from conference follow-ups may also constitute pre-marketing depending on whether it falls within the above definition.

Is it reverse solicitation if a contact from a conference requests information about the fund?

If at the conference, one only talks about generic fund sponsor corporate identity, history, team, fund strategies, performance to date etc, then can subsequent contact from a potential investor, with whom the initial contact was made at a conference, constitute reverse solicitation?

If a pre-marketing notification filing has been filed in respect of the proposed fund (see below discussions), the answer to this question bears little practical difference because in filing for pre-marketing, you are effectively barred from admitting investors by reverse solicitation for a period of 18 months from the date you start pre-marketing as stated in the notification filing.  Although it is not clear in the legislation how the prohibition will be applied, it would appear the industry is taking the view that this applies on a country-by-country basis, dependent on whether a pre-marketing notification has been filed in that country.

If a pre-marketing filing has not been undertaken, it may be arguable whether this is genuine reverse solicitation, and legal advice should be sought to confirm this. In ESMA’s statement of 13 January 2021, a year after Brexit, ESMA specifically raised the issue of questionable practices relying on reverse solicitation and noted that: “As for the means of such solicitations, ESMA reminds firms that every communication means used, such as press releases, advertising on internet, brochures, phone calls or face-to-face meetings should be considered to determine if the client or potential client has been subject to any solicitation, promotion or advertising in the Union on the firm’s investment services or activities or on financial instruments.”

Broadly speaking there is now an acceptance that reverse solicitation is not a marketing strategy.  For fund sponsors engaging an EU regulated placement agent, those distributors would also be keen to ensure that the fund is approved for pre-marketing or formal marketing before discussions or distributions of any materials with fund specific information begin. This has been brought in to focus recently, when in April 2022 a French distributor was fined and banned from marketing for 5 years by the Autorité des Marchés Financiers for actively marketing funds which were not actually approved for marketing in France.

So I am pre-marketing, what regulatory cover do I need?

This varies depending on the current level of regulatory permissions, and the location of the fund sponsor.

EU regulated AIFM – For sponsors with an EU regulated AIFM, the regulatory risk is easy to manage by filing a notification filing with the home regulator specifying amongst other things, the countries in which they wish to pre-market the fund. The home regulator will then notify the relevant regulators in those countries included in the notification. This aspect deals with the fund itself being approved for pre-marketing. If no placement agent is engaged, an EU AIFM is permitted to undertake the activities of pre-marketing themselves. The notification filing can be undertaken within 2 weeks of having started pre-marketing so can be done after attendance at the conference.

Non-EU fund sponsors – By appointing Langham Hall as the EU regulated host AIFM, the non-EU fund sponsor can benefit from pre-marketing passport in the EU. In this solution, Langham Hall will file the pre-marketing notification and oversee the sponsor/distributor during the pre-marketing period. This solution can be in place within a couple of weeks (although should really be discussed before the commencement of pre-marketing, i.e., prior to your attendance at the EU conference).

The alternative to using a host AIFM is to navigate the pre-marketing rules on a country-by-country basis.  Because the CBDD states the national rules “should not in any way disadvantage EU AIFMs vis-à-vis non-EU AIFMs”, this does not mean a reversion back to pre-CBDD days and relying on a pre-marketing matrix formulated at the outset. At the very least it is expected there will be a notification requirement. However, this is far from clear for many countries and in some countries pre-marketing by a non-EU fund sponsor may be prohibited altogether. It is also unclear if non-EU fund sponsors may undertake the activity of distribution without an EU regulated entity’s involvement.

It should be noted that filing a pre-marketing notification does not oblige the fund sponsor to go down any set route with respect to formal marketing. Depending on the appetite and requirements of investors as may be gauged during the pre-marketing period, the fund sponsor can choose to admit investors by way of formal permissions under NPPR, set up a fund in the EU that benefits from the AIFMD passport, or decide it is not cost effective to go down either route. In any case, no investors should be admitted by way of reverse solicitation as per discussions above for a period of 18 months after commencing pre-marketing.

Summary

Fund sponsors should carefully consider their intentions and what they will share during and as follow up to attendance at conferences as some activities may fall under pre-marketing.

Pre-marketing regulation has dual aspects: (i) for the (potential) fund itself to be pre-marketed (achieved by notification filing); and (ii) for the party undertaking the distribution to be regulated in the EU (either by engaging an EU regulated placement agent or engaging a third party AIFM, who can also do the filing, and provide distribution cover).

Langham Hall can assist with providing solutions for non-EU fund sponsors undertaking pre-marketing. This solution does not oblige the fund sponsor to undertake any other services with Langham Hall.  In the event the fund sponsor wishes to market under the NPPRs, Langham Hall can assist with providing Depositary Lite services (required for registering in Denmark and Germany) and Annex IV reporting.  If the fund sponsor wishes to benefit from the marketing passport via a Luxembourg fund (usually as a parallel to a non-EU fund), we can assist with the administration, domiciliation, Host AIFM and Depositary services for your fund.

Given Langham Hall’s presence in fund jurisdictions such as Hong Kong, Singapore and New York, fund sponsors in North America and Asia can bring all administration services for both parallel vehicles under one roof if preferred.

Please note the information contained in this article is for general purposes only and does not purport to constitute legal advice from Langham Hall.  Please do not rely on the contents of this article without getting proper legal advice.

No results found.
There are no results with this criteria. Try changing your search.

Join our newsletter

By subscribing you agree with our Privacy Policy

By inputting your details you consent to being contacted by Langham Hall.
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.