LATEST INSIGHTS
Tasman Capital Partners Fund IV reaches first close and completes initial investments
The Barbell Effect: Why we are in our spinout era
The private equity industry is undergoing a quiet structural shift, one that is reshaping how capital is allocated and for the right managers, where the most compelling opportunities lie. At one end of the market, household names, Apollo, KKR, Carlyle and their peers are consolidating LP relationships at scale, offering breadth, brand and reliable returns across diversified platforms. At the other, a new generation of focused spinout managers is attracting serious institutional attention for a different reason: they consistently outperform.
For GPs considering a spinout or raising a first institutional fund, understanding this dynamic is more than academic. It defines the opportunity.
Why first-time funds outperform
The performance case for emerging managers is well-established and the data is compelling. Among fully realised buyout and growth private equity funds, the average Fund I has delivered an IRR almost 20% higher* than for a Fund IV and beyond.
The explanation is straightforward: alignment. First- and second-time managers typically commit a meaningful share of their own capital to the fund, closely aligning their interests with those of their LPs. At established platforms, senior professionals often divide their time between investing, marketing and managing internal complexity. At a spinout, the entire team is focused on one thing: delivering returns from a standing start. When the first fund is your firm's entire reputation, the incentive to perform is unambiguous.
There is also a structural advantage at play. Smaller, more focused funds are simply better positioned to access opportunities that larger vehicles cannot. A concentrated strategy targeting a specific sector or geography allows for deeper sourcing networks, faster decision-making and a closer relationship between GP and portfolio company. These are not incidental benefits, they are structural edges that compound over a fund's life.
The LP calculus
LPs are increasingly attuned to this. While the largest allocators will always maintain relationships with global platforms for the scale and predictability they offer, a growing cohort is carving out meaningful allocations to emerging managers precisely because the return profile is differentiated.
The trade-off is real. Deploying significant capital across multiple smaller vehicles is operationally more demanding than writing one or two large tickets to established names. Not every LP is structured to do it efficiently. But those who have built the frameworks to access this part of the market, through dedicated emerging manager programmes, co-investment rights or direct relationships, are capturing alpha that the rest of the market is systematically underweighting.
According to Preqin, first-time funds have outperformed established funds on average every year since 2005 and carry a higher probability of generating returns above 25% IRR. For LPs willing to do the work, the reward has been consistent.
Building the foundation that earns institutional capital
For those building something new, the data is encouraging. But performance potential and institutional credibility are not the same thing, and LPs are sophisticated enough to distinguish between them.
The most successful first-time funds start LP conversations with the right infrastructure already in place. Operational due diligence is a staple of the underwriting process for a majority of investors, and so knowing that a manager has the right operational and regulatory infrastructure behind them gives LPs confidence from the get-go. Simply put, it takes another “reason to say no” off the table.
This is where the choice of service providers, including fund administrator, becomes a strategic decision rather than an operational one. The right administrator brings more than processing capability. At the start of a fund's life, when track record is limited and the GP is asking LPs to back a team on potential, the quality of the operational infrastructure sends a signal. It demonstrates that the GP understands what institutional investors require, has the rigour to deliver it and is building a firm designed to scale.
For a startup manager, having a partner that can handhold from day one whilst also giving investors confidence in the operational robustness of a platform can be one more decision that moves the needle in the direction of success.
As an independent, partner-led firm, Langham Hall has been supporting new fund managers for over 20 years. As a result, we have deep experience handholding clients through the setup of new businesses. Clients gain access to experienced Partners who can guide them through the operational, regulatory and structural considerations involved in launching an investment product for the first time. Please do get in touch if you would like to discuss further.
Introducing First Close - The Emerging Manager Podcast from Langham Hall
Langham Hall is pleased to introduce First Close, a new podcast series in which Tom Pinnell, Head of Commercial, Europe, sits down with emerging private equity managers and the people who work alongside them to talk honestly about what it takes to build a private equity firm from scratch.
Each episode delves in to moments that matter the most. The highs, the lows, the successes and the failures on the road to the first close.
Our first guest is Mark Williams, Co-founder and Managing Partner of Goldenpeak, one of the most exciting new private equity firms to have launched in recent years and a manager who recently completed one of the fastest first-time fundraises we have seen in this market. Tom recently sat down with Mark to discuss the journey from idea to first close, why now, and what truly sets Goldenpeak apart.
Available on Spotify, Apple Podcasts and all major platforms.
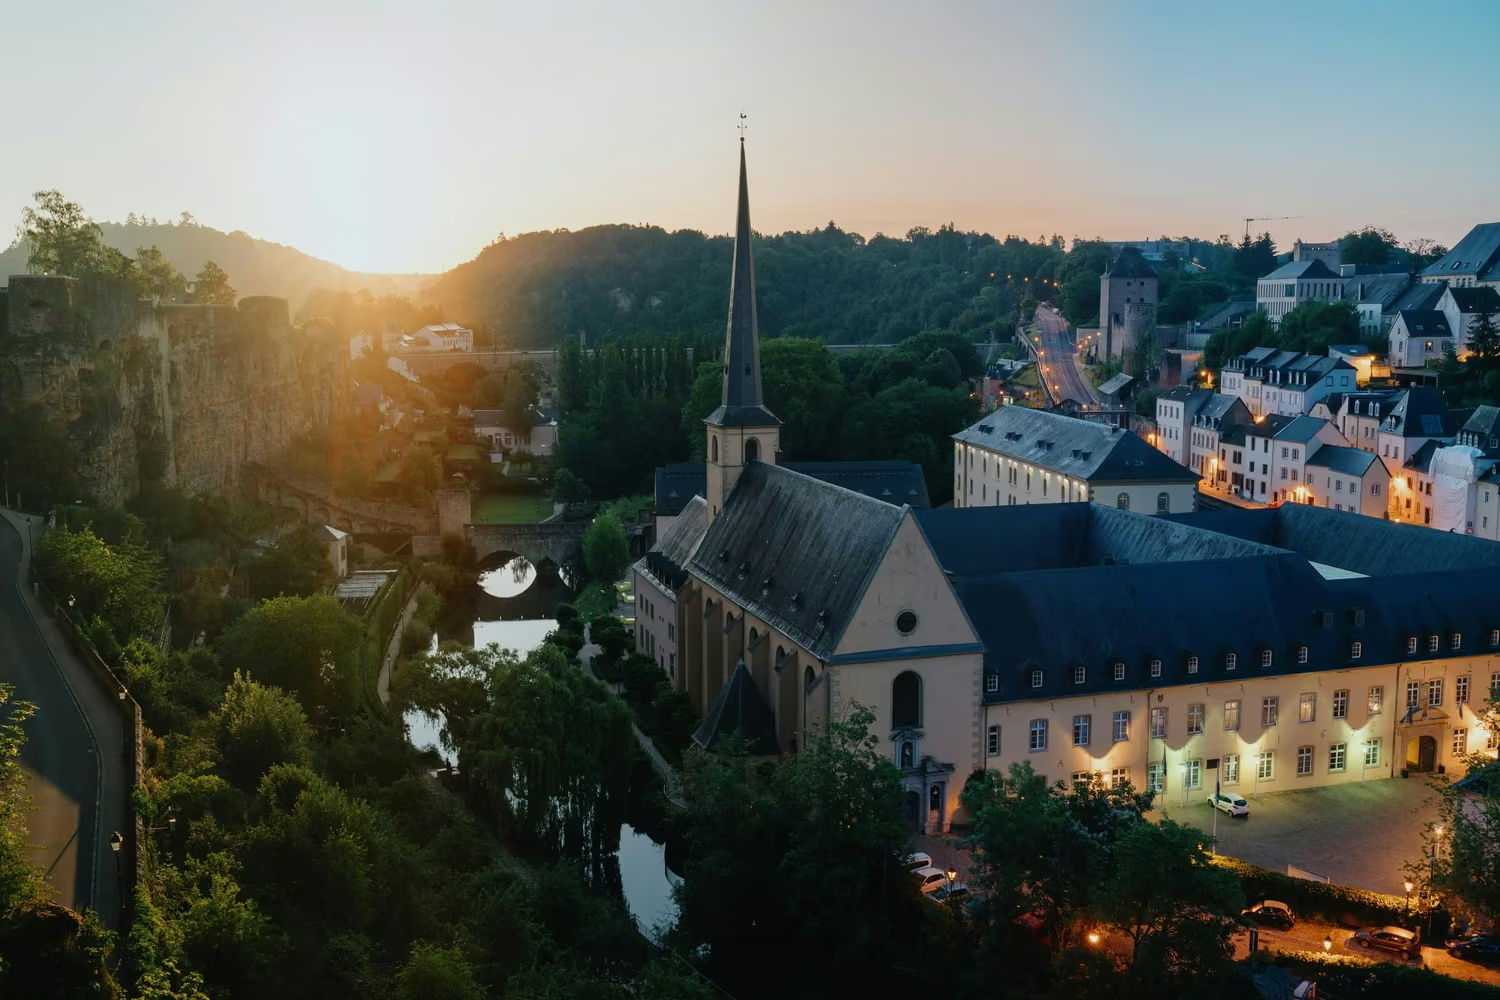
Langham Hall welcomes back Tatyana Boger as Head of Fund Administration in Luxembourg
Langham Hall has welcomed back Tatyana Boger as Head of Fund Administration in Luxembourg, strengthening its fund administration leadership as clients continue to use the jurisdiction for increasingly sophisticated cross-border private fund structures.
Tatyana returns after a period as Partner at a professional services business in Luxembourg. Having originally joined Langham Hall in 2015, she went on to spend more than ten years with the firm, playing a central role in the development of the Luxembourg business and progressing through senior positions before later leading group-wide strategic projects.
Her return brings institutional knowledge and operational experience at a time when managers are navigating increasingly complex governance, reporting and structuring requirements. She will lead the Luxembourg fund administration business, working closely with colleagues across client service, operations, depositary and AIFM functions.
Tatyana began her career with Deloitte in Cyprus and Luxembourg. Across two decades in professional services, she has developed broad experience across private markets, fund operations and client delivery.
Her appointment reinforces the firm’s commitment to hands-on senior leadership, technical discipline and long-term client relationships in a jurisdiction at the heart of European private fund activity.
Elijah Kanevskiy, Head of Luxembourg at Langham Hall, said: “Luxembourg is becoming more operationally demanding for fund managers, particularly as reporting, governance and investor expectations continue to rise. Tatyana brings technical depth, practical judgement and a strong understanding of how to build teams and operating structures that work in that environment. This appointment strengthens our team and gives clients direct access to someone with real depth across administration and governance.”
Tatyana Boger, Head of Fund Administration, Luxembourg, Langham Hall, added: “Langham Hall has always been a business where senior people stay close to the work and take real ownership for clients. That culture matters. I am pleased to return at a time of continued growth and look forward to working with the team to support clients with the precision, pace and judgement they expect from us.”
Switching depositaries: Less daunting than you think
A full depositary relationship is typically set as part of the launch process, often under time pressure and as one item on a long list. Depositary-lite may be agreed even earlier, particularly where a manager needs to name a provider for marketing purposes. Either way, the arrangement can remain in place long after the fund and the manager’s operational needs have evolved.
Fast forward five years: the strategy has matured, AUM has grown and the fund structure may be more complex. But the oversight relationship has not necessarily kept pace. For finance and compliance teams, triggering a review feels like creating work. There is the comfort of the familiar and, in some cases, concern about regulatory scrutiny. That hesitation is understandable. But where the relationship is no longer efficient, responsive or proportionate, staying put can cost money, management time and operational risk.
Why switch?
In our experience, the managers who make changes proactively, rather than reactively, tend to do so when one or more of the following becomes difficult to ignore.
Service quality has eroded. Queries take longer. The named contact changes without notice. Work is handed off to junior team members without senior oversight. Strict internal procedures are followed to the letter, whilst a reluctance to think beyond the script leads to repeated requests for information that is not relevant or does not exist.
Your depositary or depositary-lite provider should be a trusted partner: consultative and more effective year on year as institutional knowledge builds on both sides. It should not be absorbing increasing amounts of time.
What the process actually looks like
The perception of a depositary change as a major operational undertaking is, in most cases, disproportionate to the reality. A well-managed transition typically runs over eight to twelve weeks from appointment of the new provider to full go-live.
For more complex structures, or where the outgoing depositary is uncooperative, that timeline can extend, but it remains manageable. Most of the work comes from the need to build out new investor and asset registers. These are the foundation everything else sits on: a structured record of who owns what, drawn directly from the administrator’s books and reconciled against the underlying fund documents and capital activity. Once they are complete, the relationship runs as normal, without the need to work on backdated fund activity.
The key workstreams are not unfamiliar territory for a CFO or CCO:
- Legal documentation: new agreements with the incoming provider, amendments to fund documents where required and any ancillary arrangements with the administrator.
- Regulatory notification: a change of depositary requires notification to the relevant regulator, but this is generally procedural rather than an approval process.
- Operational handover: data transfer, account creation, process mapping and oversight procedures.
- Investor and asset registers: establishing the records required for ongoing oversight and monitoring.
The process mapping stage is key and is often where the greatest efficiency gains can be made. In practice, this means agreeing a monitoring plan for different fund activities: what will be reviewed, what evidence will be needed and how more complex transactions or capital events will be tested.
One of the most common frustrations with incumbent providers is their lack of flexibility in their own testing processes and poor understanding of illiquid asset classes. Choosing a depositary who adapts their processes to how your funds operate in practice is crucial, with understanding and mutual agreement built at this stage leading to a smooth relationship over the life of the fund.
The transition date itself is also important. At the point of change, one provider stops acting and the other begins. The outgoing provider remains responsible for the period during which it acted, while the incoming provider assumes responsibility from appointment. In practice, the process is less about reopening historic activity and more about ensuring the new relationship starts with clear records, agreed processes and a practical understanding of the fund.
What to look for in a new provider
Selection criteria for a new provider should be driven by what matters to the manager’s specific operation, not a generic checklist. That said, a few questions tend to separate the good conversations from the average ones:
- Does this provider actually understand your fund structure and asset class? Work that touches private credit, real assets, or complicated deal structuring requires genuine expertise. A provider with tailored processes and deep experience with each asset class will need to ask fewer questions to complete its work and will only ask for the documentation that is genuinely required.
- Who will you actually deal with? The pitch will always involve senior people. The test is whether those senior people remain involved once you are onboarded or whether the relationship migrates to a service desk. Ask for references from clients of similar size and complexity, and ask them specifically about day-to-day responsiveness, as well as continued senior engagement.
- How is the service team structured? Many providers now rely heavily on offshore or junior delivery teams. Managers should understand who will handle the work day-to-day, where they are located, what training and supervision they receive and when senior judgement is brought in.
- Will the interactions and operational impact on your team actually improve? For many managers, the issue is not one major failure but “death by a thousand cuts”: repeated information requests, rigid checklists and too much time spent revisiting the same points. A strong provider should be able to show how it would reduce that friction in practice, including by workshopping a complex transaction and pointing to relevant peer-manager migration experience.
The cost of doing nothing
There is a version of this argument that frames a switch as a bold or disruptive move. We would suggest the opposite framing. The bold move is the one most managers are already making: staying in a relationship that is not delivering, year after year, because the alternative feels complicated and low priority.
The depositary relationship is operationally material and carries regulatory significance. It intersects with everything the finance team does and can take up a meaningful share of their time.
The mechanics of a change are manageable, the process is understood, the regulatory framework accommodates it and the benefits are tangible. For most managers, the hardest part is simply recognising the relationship has stopped working and making the decision to address it.
How U.S. Managers are redefining fund administration
The mid-market shift: Why managers are rethinking the finance operating model
Outsourcing was once a question of cost and capacity. That framing belongs to a different market. Many scaled, offshore-heavy or process-led models work well in stable conditions and falter under pressure. As structures become more layered and investor questions more specific, the model itself, not the volume of work, determines whether the finance function can keep up.
That is why changing administrators is rarely just a vendor decision; it is a decision rooted in trust. Managers are not simply buying a reporting process; they are choosing a seasoned team that understands where the operational risks sit and can work seamlessly alongside the internal finance function.
The pressure points are familiar enough. Side letter obligations have multiplied. Continuation vehicles introduce structures the current model was not designed to carry. An audit query, a late workpaper change or an investor question on a specific transaction may require someone to read the LPA, not follow a process.
These are the moments that separate administration that simply processes from administration that exercises judgment. Strain does not usually appear as a single failure. It shows up in the work required to keep the process moving: manual intervention, senior oversight, repeated reconciliation and reliance on knowledge held by a small number of people.
From outsourcing to operating partnership
Modern managers require the best of both worlds: full visibility of their data, supported by strong fund accounting infrastructure and experienced judgment. The most successful relationships transcend traditional service models to operate as a true extension of the in-house team. This gives managers confidence that, when the work becomes more complex or time-sensitive, they have a sophisticated, reliable team ready to help navigate the issue with them.
That distinction matters most during transition. Moving administrator, or outsourcing for the first time, requires a clear view of where the risks usually sit: historical data, entity structures, investor records, open audit points, reporting calendars and the informal knowledge that often sits outside the system.
In one recent migration, our team brought across five years of historical data for more than 100 entities, structuring and reconciling it into a single source of truth for reporting, audit work and investor queries. That kind of transition depends on planning, well-structured data and people who understand the platform and the fund documents behind it.
For CFOs, the value is not simply more capacity. It is better judgment under pressure. Internal teams know their own structures deeply. Experienced administrators see similar questions across dozens of managers, fund types and market conditions. That pattern recognition becomes valuable in moments that do not fit a standard process.
The value of better systems is not faster reporting alone. It is the ability to interrogate the record without rebuilding the analysis each time, and to give audit, investor relations and finance a single, computable record to work from. Without that, every investor query becomes a forensic exercise.
Technology only delivers that when it is built on the right architecture. The wrong system creates new dependencies. The right one removes them, but only if there are people around it who can read fund documents, weigh audit implications and resolve ambiguity when timing is tight.
Responsiveness is now a risk issue
During reporting periods, timing matters. An investor comment, audit question or late change to a workpaper may need both judgement and access to the underlying record. If the answer depends on a team in another time zone coming online, making the change and sending it back for review, a small issue can quickly become a delay.
Some global delivery models depend on handoffs, and handoffs cost time the CFO does not have at quarter end. The risk is not that work fails to get done. It is that certainty arrives too late to be useful.
Three things the strongest firms understand early
The firms that get this right are not necessarily those with the largest finance teams. They tend to recognize three things earlier than their peers.
- First, institutional readiness is a quality of the operating model, not a stage of growth. A mid-market manager can be more institutionally ready than firms several times its size.
- Second, the platform is tested in the side conversations, not on the reporting calendar: the continuation vehicle that does not fit the template, the LP question that requires the document to be read rather than the report rerun, or the fundraising deadline that collides with quarter-end.
- Third, changing administrator or outsourcing for the first time is not just a procurement decision. It is a redesign of how the finance function will operate day to day. The provider decision matters, but so does the model around it: who owns the record, how historical data is reconciled, how quarter-end is protected, how investor questions are handled and how quickly the team can get to a reliable answer. Even the right provider can disappoint if the migration only changes the name on the service agreement.
By the time the operating model is visibly under strain, the business has usually already outgrown it.
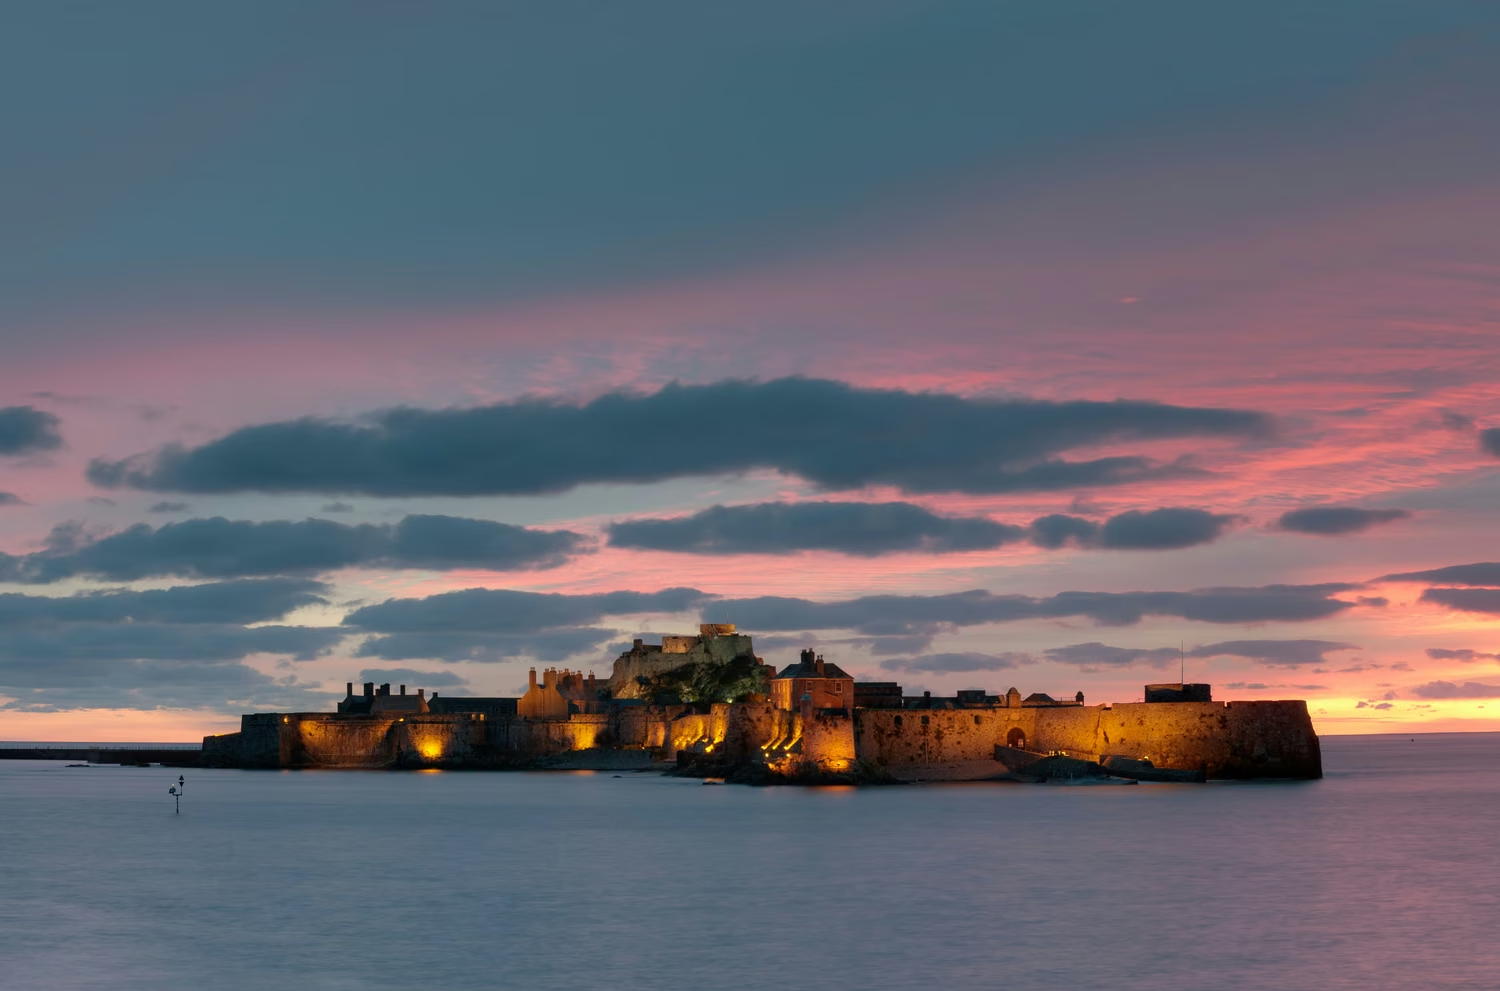
Langham Hall appoints Chris Young as Executive Director in Jersey
Langham Hall has appointed Chris Young as an Executive Director in Jersey, strengthening its senior leadership across private equity and real estate fund services.
With nearly 15 years’ experience in the Jersey financial services market, Chris plays a key role in supporting client delivery, strengthening governance frameworks and contributing to Langham Hall’s growth agenda. He works closely with clients and internal teams to deliver high-quality outcomes and maintain strong relationships with global fund managers.
Jersey is a leading international finance centre, recognised for its robust regulatory framework, technical expertise and longstanding credibility with institutional investors. Langham Hall Jersey is well established in the market and is known for its specialist fund expertise, strong governance focus and consistently high standards of service across private equity and real estate structures.
Prior to Langham Hall, Chris held senior leadership roles across fund services, including Head of Service Delivery for Private Equity and Executive Director. He began his professional career at PwC in its assurance practice, qualifying as a Chartered Certified Accountant (ACCA), before moving into risk management within the fund services sector.
His experience spans both private equity and real estate funds, combining strong technical capability with commercial awareness and a pragmatic approach to operational delivery. He brings a particular focus on process improvement and innovation, supporting the development of the business whilst maintaining rigorous quality and service standards.
In his role as Executive Director, Chris is responsible for supporting senior teams, strengthening client relationships and contributing to the continued development of Langham Hall’s Jersey business. He has also recently been appointed to the Langham Hall Jersey Board.
Chris Marshall, Partner and Head of Jersey, Langham Hall, said: “Chris brings strong experience across private equity and real estate fund services, together with a clear understanding of service delivery, governance and operational leadership. He is an important addition to our senior team in Jersey and I am very pleased to welcome him to the business.”
Chris Young, Executive Director, Jersey, added: “Langham Hall stood out to me for its strong reputation, the quality of its people and clear ambition for growth. I look forward to building on the Jersey team’s strengths and working closely with clients and colleagues in Jersey and across the wider group.”
Recognising our newly qualified ACCA professionals
We are pleased to recognise colleagues across Langham Hall who have recently completed their ACCA qualifications and achieved fully qualified status. This is a significant milestone, reflecting years of commitment, perseverance and professional development.
To reflect on this journey, we caught up with Jacques Amy, Senior Fund Accountant in our Jersey office, to discuss what qualifying with ACCA meant to him and the support he received along the way.
Q&A with Jacques Amy, Senior Fund Accountant
What does becoming ACCA qualified mean to you?
Passing my final exam brings a great sense of relief and pride. I have been at Langham Hall for coming up to six years now and five and a half of those I have been studying towards my ACCA, so it is a great relief to get them done.
On a personal level, it finally means that I am able to close a long chapter of studying, from school to university and then onto professional exams.
How did Langham Hall support you through your studies and exams?
Outside of financial support, Langham Hall’s apprenticeship model focuses on developing staff from within, allowing me to take ownership of the process and develop at my own pace.
Many of the managers in the team have been through the experience themselves recently, so they are up to date with how the exam process works and able to provide valuable insight, tips and tricks.
Langham Hall has given me time off to attend full time, in-person tuition courses, allowing me to focus fully on my studies and not worry about work pressures.
What advice would you give to anyone interested in studying ACCA or a career in accounting?
My advice to anyone considering the path would be to give it a go. It can be tough at times, but also rewarding, and achieving the full ACCA status opens the door to so many possible future opportunities.
Jacques’ experience reflects a wider achievement across the business.
Whilst experiences vary, colleagues across Langham Hall’s jurisdictions often describe a shared sense of pride and relief when completing their final exams. Qualifying represents a significant personal milestone, reflecting the effort required to balance study alongside client work and bringing renewed confidence as they take the next step in their careers.
Supporting professional qualifications at Langham Hall
At Langham Hall, we support colleagues throughout their professional qualification journeys through structured study support, mentoring from experienced professionals and practical, hands-on exposure in real-world client environments.
We believe investing in professional development is essential, not only for individual career progression but for maintaining the high standards of expertise and service we provide to our clients.
Congratulations to all our newly qualified ACCA professionals across the business on this well-deserved achievement.
Langham Hall supports Atlas Health Capital’s £400 million debut fundraise
Langham Hall has supported Atlas Health Capital on the successful raise of its debut private equity fund, Atlas Health Fund I (the “fund”), at £400 million. The fund hit its hard cap and was oversubscribed at final close, less than four months after fundraising began.
The fund will focus on buyout opportunities across selected European healthcare markets, including the UK and Ireland, DACH, Benelux and the Nordics, targeting specialist subsectors in MedTech, Niche Pharma and Animal Health. Founded in 2025 by Ben Long, Atlas Health Capital brings together a team with extensive experience across top-performing private equity firms.
Langham Hall is providing fund administration services from its Jersey office and appointed representative (AR) services from its London office, supporting Atlas Health Capital from launch through to closing.
“We are delighted to have supported Atlas Health Capital on the successful close of its debut fund. As a new manager bringing together a highly experienced team, this is an important milestone and one that reflects the continued confidence investors are placing in specialist healthcare strategies. We look forward to supporting the team as they move into their next investment phase.” – Chris Marshall, Partner, Head of Jersey, Langham Hall
Atlas Health Capital was advised by FirstPoint Equity as lead placement agent and Macfarlanes as legal counsel.
なぜ日本では投資信託が引き続き主流なのか
日本において投資信託が広く用いられているのは、単なる慣習によるものではありません。それは、投資家が投資戦略にアクセスし、流動性を管理し、資産を保有する方法に長く適合してきた構造であるためです。
この点を理解するうえで、投資信託と組合型ファンドの違いは重要です。これは単なる法的または技術的な比較ではなく、投資対象や市場環境に応じてファンドの仕組みがどのように形成されてきたかを示しています。
上場市場に適した仕組み
投資信託は、日本の戦後資本市場の発展とともに普及しました。上場証券を一般投資家向けに分かりやすくパッケージ化し、分散投資の機会を提供する役割を果たしてきました。その結果、日々の取引や標準化された商品設計といった特徴とともに、公開市場投資の代表的な手段として定着しています。
その有用性は、主に三つの要素に支えられています。
第一に流動性です。投資信託は、定期的に価格が付され売買可能な資産に適しています。上場市場と整合する形で、継続的な申込と解約を可能にします。
第二に税制です。信託内部での取引に対する課税が繰り延べられる仕組みがあり、長期投資家にとって魅力となっています。
第三に流通性です。投資信託は大量に組成し、広く販売することが可能です。この特性は、日本のリテール投資市場と高い親和性を持っています。
組合型ファンドが適する場面
一方で、組合型ファンドは異なる役割を担います。
組合型ファンドは、投資対象が非公開または流動性が低く、段階的な資金投入や長期的な保有が求められる場合に、より適しています。プライベートエクイティ、不動産、プライベートレンディングといった分野では、資産の取得や売却が一定のタイミングに依存し、日々の取引を前提としないことが一般的です。
こうした場合、組合型の構造が柔軟性を提供します。資金は必要に応じてコールされ、投資機会に応じて段階的に投入されます。長期的な視点とコントロールを前提とした投資に適した設計です。
異なる税務上の特徴
税制上の扱いも異なります。組合型ファンドには投資信託のような課税繰延の仕組みはなく、利益は発生した年に課税されます。ただし、取引頻度が低く保有期間が長い戦略では、資金の投入も異なるリズムで行われます。構造はその実態を反映しています。
日本市場から見えること
重要なのは、ファンドの仕組みは単独で存在するものではないという点です。市場環境に適合することで初めて、その構造は長期的に機能します。
日本において投資信託が主流であり続けているのは、上場資産、リテール投資家、流動性への期待、そして確立された販売チャネルと整合しているためです。一方で、これらの前提が当てはまらない領域では、組合型ファンドが補完的な役割を果たしています。
海外マネージャーにとっての示唆
海外のファンドマネージャーにとって重要なのは、日本でどの構造が使われているかではなく、なぜその構造が選ばれてきたのかを理解することです。
歴史、税制、流動性はいずれも重要な要素ですが、出発点は常に同じです。投資対象の性質が、それを支えるべきファンドの形を決定します。
ご質問やご相談がございましたら、お気軽にご連絡ください。
Join our newsletter
By subscribing you agree with our Privacy Policy