LATEST INSIGHTS
Tasman Capital Partners Fund IV reaches first close and completes initial investments
Langham Hall relocates London headquarters to Broadwalk House
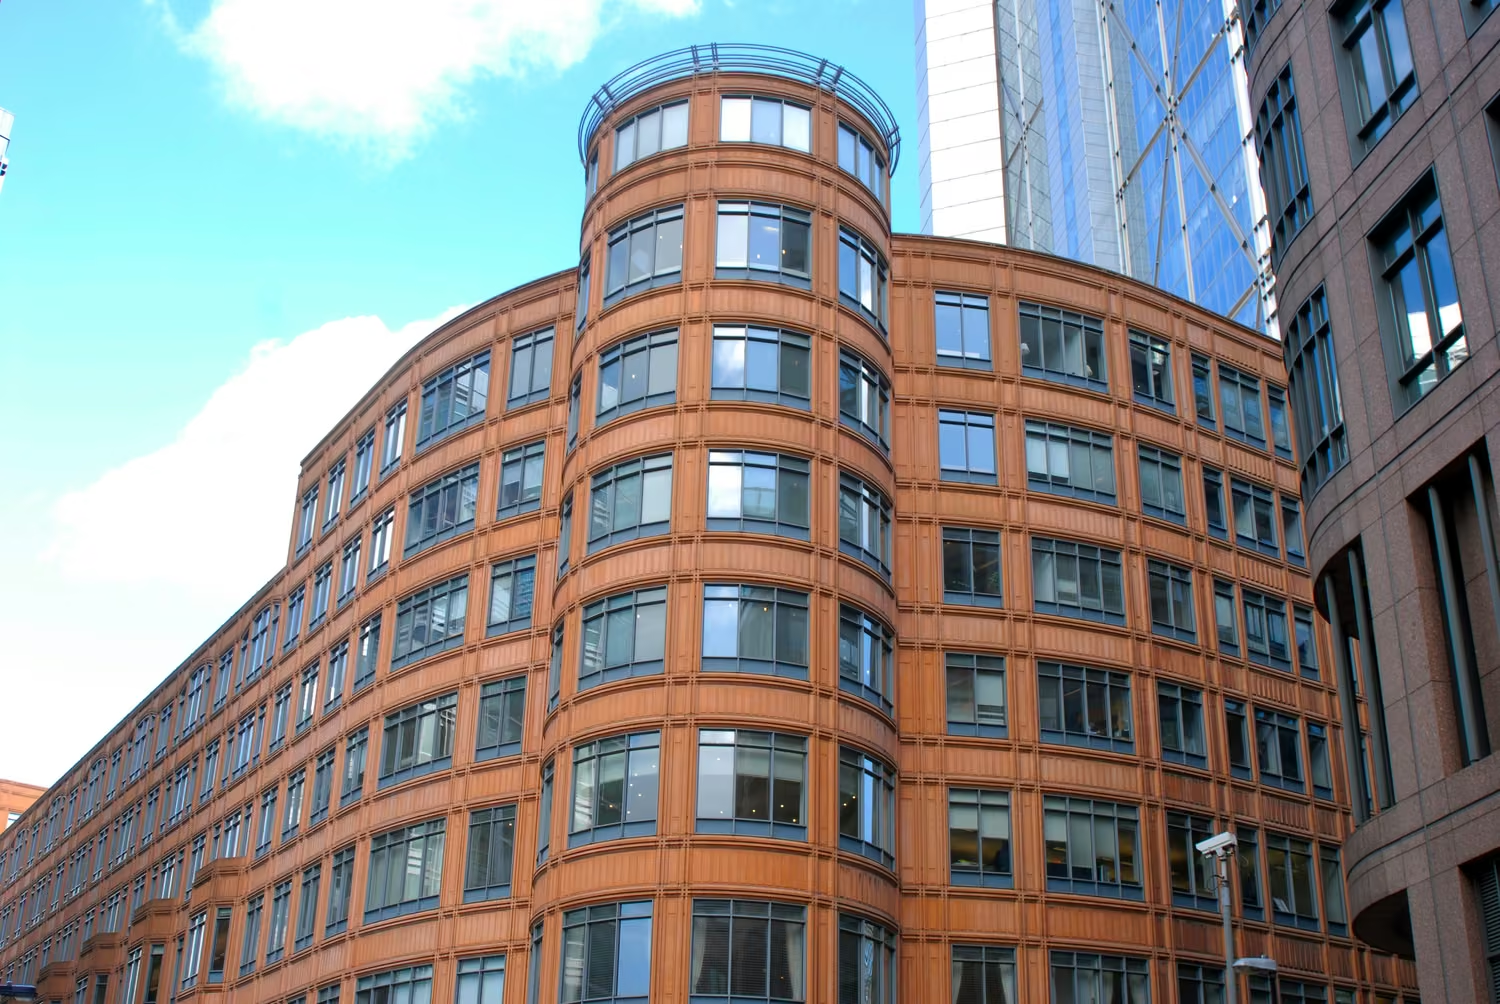
Langham Hall has relocated its London headquarters to Broadwalk House, marking a significant milestone for the firm as it continues to scale its UK and international platform.
The move brings Langham Hall’s London team into a newly refurbished 20,335 sq ft office close to Liverpool Street, placing the firm at the heart of the City’s professional services district. The relocation provides capacity to support the firm’s growing London workforce of around 250 professionals, alongside enhanced space for collaboration, training and client engagement. Langham Hall has taken two floors at Broadwalk House, which is owned by British Land.
London remains a core market for Langham Hall, supporting private equity, real estate, infrastructure and credit fund managers with fund administration, AIFMD and depositary services. The move reinforces the firm’s client-facing presence, close to fund managers, advisers and the wider funds ecosystem.
Richard James, Head of Europe commented, “The move to Broadwalk House is an important step for our London business. It reflects both the scale we have reached and our long-term commitment to London as a global centre. The new office gives us the space and flexibility to support our people, work closely with clients and continue investing in the infrastructure that underpins high-quality delivery.”
Rob Short, Managing Partner commented, “London is where Langham Hall began and, as we have expanded internationally, it has remained an important location for European and increasingly US clients. We have applied the same principle globally, building teams close to our clients rather than relying on overseas outsourcing.”

Managing Partner's Update 2026
As we begin 2026, I would like to extend my best wishes for a happy and successful year ahead. I also want to share an update on Langham Hall and our expectations for the year to come.
As private markets continue to adjust to the new normal, there are early signs of stabilisation. Fundraising remains selective and exit activity uneven, but high-quality managers are returning to the market and we are seeing an abundance of new firms and spin-outs. In what is often described as a barbell environment, investors are showing the strongest conviction towards either clearly differentiated specialist strategies or scaled platforms, and selectivity has increased across the board.
We expect 2026 to bring a gradual improvement in liquidity and a more constructive fundraising backdrop, supported by continued secondary activity and a steady reopening of M&A. At the same time, expectations on transparency, governance and reporting continue to rise. Managers and investors increasingly want timely, decision-useful information, and greater confidence in the data behind it.
Langham Hall now has 900 people across Europe, Asia and the US and remains owned exclusively by management. This ownership structure underpins our priorities for 2026, which centre on client leadership, technical excellence and continued investment in our teams.
We will also continue to develop Wolfram and our computable data strategy, with a practical focus on improving data quality, reporting efficiency and the accessibility of client information. Across our offices, we remain focused on delivering joined-up support for managers and investors, combining local expertise with the depth of a global platform.
We have also continued to invest in leadership and in the foundations of our professional services. In 2026, Richard James will continue as Head of UK and will also take on the role of Head of Europe. This will strengthen our European platform and provide additional depth and support to jurisdictional leadership.
I would like to express my sincere gratitude to our clients and advisers for your continued trust and support.
Best wishes,
Rob Short
Managing Partner

Cayman update: PPoC residency and CIMA survey
As we begin 2026, we are writing to highlight two Cayman regulatory updates:
• Principal Point of Contact (PPoC) residency requirement
• Cayman Islands Monetary Authority (CIMA) Prudential Information Survey requirement
1. The PPoC residency requirement
What is changing
From 1 January 2026, a Cayman financial institution (FI) must appoint a PPoC who is resident in the Cayman Islands. Most Cayman private funds are FIs, so existing appointments should be reviewed.
Who is affected and when
• Existing FIs (registered on the DITC Portal on or before 31 December 2025): transition period to 31 January 2027 to move to a Cayman-based PPoC
• New FIs (registered since 1 January 2026): must appoint a Cayman-based PPoC on registration
How is this completed
• Appointment or change is filed via the DITC Portal
• The PPoC liaises with the Department for International Tax Cooperation (DITC), receives regulatory communications and, where required, adds a secondary user on the DITC Portal for FATCA and CRS
Why it matters
Failure to appoint a Cayman-based PPoC may attract an administrative penalty of up to KYD 10,000.
2. CIMA Prudential Information Survey (Registered Persons)
What is changing?
CIMA now requires Registered Persons (including SIBA investment advisers) to submit a Prudential Information Survey via the REEFS Portal. CIMA has issued a notice and a completion guide.
Deadline
For the 2025 calendar year, submission is due on or before 31 March 2026 via the REEFS Portal. Cayman registered office agents submit on your behalf.
How is this completed?
• Review CIMA’s notice and completion guide
• Prepare responses (we can provide a pre-filled template on request)
• Coordinate submission with your Cayman registered office agent via REEFS
Why it matters
Although the survey appears statistical, submission is a mandatory regulatory requirement for in-scope Registered Persons.
More information
• CIMA’s notice
• CIMA’s completion guide
How Langham Hall can help
Langham Hall works with Cayman partners to coordinate Cayman-based PPoC appointments and DITC filings. We also provide a pre-filled template to help Registered Persons complete the CIMA survey efficiently.
Get in touch
Please email aml.asia@langhamhall.com to discuss applicability to your structures or to request assistance with DITC or REEFS submissions.

Career reflections: Sophie Vallée-Berthold
Ten years of growth in compliance
Sophie Vallée-Berthold is Head of Compliance in Langham Hall Luxembourg and has spent the past ten years helping the office grow while strengthening its compliance framework. She reflects on how her role has evolved alongside increasing regulatory demands, particularly in areas such as AML and tax, and what she has learned about developing people through change.
Starting out in compliance
My career began in Luxembourg in 2008, when compliance was still emerging. With a law degree, I started as a Legal Advisor, which gave me my first insight into how closely regulation and business practice connect. My next role combined legal and compliance work, offering a clearer view of how the field was evolving and showing me how naturally the two areas fit together. Those early experiences are what drew me further into compliance.
I joined Langham Hall Luxembourg after my first parental leave as a part-time Compliance Officer, attracted by the flexibility and the chance to join a young business where compliance was becoming increasingly important. As the firm grew, so did the role, quickly moving to full time. It was a natural progression that allowed me to apply my legal background, deepen my expertise and grow with a firm still early in its development.
Early impressions and experiences at Langham Hall
In my first months, Langham Hall really felt like a start-up. There were only seven people in the Luxembourg office and everyone had to be ready to roll up their sleeves. I was learning a new role, a new company and an entirely new environment, all while taking on significant responsibility from the outset.
Despite the change in scale, one thing has stayed the same: the collaborative spirit that defined those early days. People share knowledge with each other and there is a sense of collective progress.
A key turning point was realising that, as I was developing, the firm was expanding just as quickly. Growing regulatory demands, especially around AML and tax, meant I was trusted with greater responsibility and soon began building my own team. Moving from doing everything myself to guiding others set the path toward a more strategic role focused on coordination, planning and people. The trust placed in me throughout has been central to my confidence and professional identity.
Growth and change
Starting in such a small team meant that learning happened in a very hands-on way. I benefitted directly from the experience and guidance of colleagues who were willing to take the time to teach and explain. It created a genuine apprenticeship environment and that way of working has remained central to Langham Hall’s culture.
Watching colleagues progress has also been a motivating part of the journey. Seeing people stay, work hard and develop into more senior roles reinforces the idea that growth here is real and achievable.
Personal reflections and proud moments
I am most proud of seeing the people I have trained grow into confident, trusted professionals. Contributing to the growth of the Luxembourg office, from a small start-up environment to a larger and more mature business, has also been a highlight, especially while maintaining strong compliance standards.
Over these ten years, I have learned that I can grow alongside significant change, that I enjoy developing others and that balancing technical work with genuine human connection is central to how I work.
I have realised that even in a serious field like compliance it is important to stay grounded, keep a sense of humour and not take oneself too seriously. Creating an open and relaxed atmosphere helps teams work better together.
Advice for new joiners
When I joined, curiosity was essential because we had to deal with everything ourselves. Even though we are now a much larger and more structured organisation, that early start-up mentality remains valuable. Do not wait for all the answers. Look around, ask questions and learn from the people around you. Collaboration is always there, but personal initiative is one of the strongest drivers of learning.
Advice for future compliance professionals
For anyone starting a career in compliance or finance, be ready for constant change. Regulations evolve and so do the businesses you support, so staying close to the detail and keeping your judgement sharp will help you stay one step ahead.

What makes a great accountant at Langham Hall Jersey
Great fund administration depends on strong fund accounting: disciplined processes, sound judgement and people who stay calm under pressure. We spoke with James Bruno, Senior HR Administrator in Jersey, about what “great” looks like and how we support long-term progression.
In fund administration, the technical work matters, but so does how people work. The best fund accountants combine analytical rigour with calm judgement, follow process with discipline, and keep learning as standards evolve.
At Langham Hall Jersey, we look for people who can handle complexity with care, build trust through accuracy, and develop quickly through structured support.
Q: What do you look for in a great fund accountant?
We look for people who combine technical rigour with good judgement. On the technical side, that means an analytical mindset, the ability to interpret complex data and spot patterns and a process-oriented approach to delivery. It also means being technically sound, with a strong grasp of accounting principles, systems and financial instruments.
Culturally, it matters just as much that someone is calm and composed, ethical and transparent and committed to continuous learning. The work evolves, so the best people stay curious and adapt as industry standards change.
Q: Why do these traits matter in fund administration?
Because clients rely on numbers they can trust, delivered on time. Strong fund accounting underpins accurate NAVs, predictable closes and clear reporting. When the operating rhythm is consistent, it reduces friction at month-end and quarter-end and helps teams spot issues earlier, before they become time-consuming fixes.
Q: What does process oriented look like day to day?
It means working in a structured way: understanding the close timetable, keeping documentation clean, following controls and making sure work is repeatable. It also means communicating early when something does not look right, so issues are resolved before they add pressure later in the close. Ultimately, it is about delivering accurate outputs on time in a way clients can rely on.
Q: What does progression look like in Jersey?
We take long-term development seriously. Langham Hall follows an apprenticeship model to support career progression, with study support available for colleagues pursuing ACCA qualifications and structured routes to grow from fund accountant roles into senior fund accountant, manager and beyond. Mentorship from senior colleagues is an important part of that journey.
Q: What makes someone progress quickly?
The people who progress fastest tend to take ownership of their development. They ask for feedback, seek out learning opportunities and stay proactive as the work becomes more complex. That mindset, combined with strong attention to detail, is often what accelerates growth.
Q: What should candidates do if they are interested in joining?
If you are looking for a place where standards are high, development is supported and progression is clear, we would welcome a conversation. Explore opportunities in Jersey or get in touch with our team to learn more.
Explore current opportunities in Jersey and across our global offices.

Langham Hall supports Goldenpeak’s £375 million debut fundraise
Langham Hall has supported Goldenpeak on the successful first and final close of its debut private equity fund, Goldenpeak Fund I LP (the “fund”), at £375 million. The fund hit its hard cap and reached its close in just over 12 weeks from first conversations.
The fund will invest in professional services and data and information services businesses across the UK and Ireland. Founded in 2025 by Mark Williams and Leon Gillespie, Goldenpeak brings together a team with extensive experience from top-performing European private equity firms. The fund has secured commitments from a group of blue-chip US and European institutional investors.
Langham Hall’s team, led by Jon Young, Partner and Head of Guernsey, provides fund administration services from its Guernsey office and appointed representative (AR) services from its London office, supporting Goldenpeak through launch and close.
Goldenpeak was advised by Weil, Gotshal & Manges and Carey Olsen and has received fundraising support from Pacenote Capital.
"We are delighted to welcome Goldenpeak to our growing portfolio of first-time managers. This is an important milestone and we look forward to supporting the team beyond its very successful first and final close."
Jon Young, Partner and Head of Guernsey at Langham Hall
Career reflections: Alan O'Neill
Learning, leading and growing at Langham Hall
Alan O’Neill is part of Langham Hall’s Office of the Managing Partner, working across systems, efficiency and people development. He began his journey in our Real Estate team and has grown through client work and leadership roles over fifteen years.
Early lessons and real impact
I joined Langham Hall when the firm was in its early growth phase in London. I had worked in finance roles at large organisations but wanted to be closer to clients and to the work, making a visible difference. From day one, Langham Hall’s culture stood out: a professional services environment with immediate client exposure and clear accountability. I enjoyed seeing the direct impact of my work on clients and the firm. Those early years were fast-paced and full of learning. I studied for my CIMA qualification alongside colleagues who have since become lifelong friends.
Opportunities for development
Langham Hall’s commitment to development has been a constant throughout my career. Two years after joining, I began building my own team, passing on what I had learned and seeing others progress in their roles. That experience reinforced the importance of developing people and supporting them to take the next step.
As I moved into a Senior Manager role within the Real Estate team, I balanced client work with team leadership before stepping into a Director position. I continued to be involved in fund administration while also taking on broader projects across standardisation and systems. Working with HR, Operations, Technical and Payments teams gave me a wider view of how our internal tools support client service.
More recently, my role in the Office of the Managing Partner has centred on firm-wide initiatives around systems, efficiency and people development.
The apprenticeship model in practice: developing talent from within
The apprenticeship model has been central to Langham Hall since I joined. The firm has always invested in people and their development through consistent training, study support and structured mentorship. This approach builds confidence, skills and judgement.
I was fortunate to have exceptional mentors who guided me through early client interactions and helped refine my technical skills. The focus was on learning quickly, taking ownership and understanding how to ease the workload of those around me. Regular one-to-one sessions went beyond day-to-day tasks, offering space for feedback and development. That experience shaped how I now approach leadership and the time I invest in others.
Alongside on-the-job learning, I have benefitted from professional coaching and external training to prepare for senior roles. The greatest influence has come from senior colleagues who shared their time and experience, encouraging me to take on new challenges with confidence.
Advice for those starting their career
My advice to anyone starting out would be to embrace the opportunities that come with a growing business.
- Be curious, take initiative and step outside your comfort zone. The exposure you gain and the lessons you learn are invaluable.
- Maintain strong relationships with clients, colleagues and mentors. Our culture is built on collaboration and support, which makes the work rewarding.
- Focus on making life easier for the team around you; that mindset accelerates both learning and trust.
Reflections on the journey
The business has grown in ways that are almost unrecognisable from when I joined, yet our core values have remained constant. I am proud to have been part of that journey. The professionalism, commitment and shared ambition at Langham Hall are what make it such a special place to build a career.
Explore opportunities
Learn more about our trainee programme and experienced hire opportunities to develop your career at Langham Hall.
Fairness in private asset funds: waterfalls and equalisation
Private asset funds are growing in prominence across Asia and with them comes renewed attention on how value is shared between managers and investors. Behind the headlines of performance and capital flows lies a critical question: fairness.
Fund structures are designed to align the interests of general partners (GPs) and limited partners (LPs), but conflicts emerge quickly when it comes to compensation. Carried interest, management fees, hurdle rates and equalisation provisions all determine who gets paid, when and on what basis.
Take waterfalls. Should carry be calculated on a deal-by-deal basis, allowing managers to take success fees on winning deals while losses remain uncovered? Or should the portfolio be viewed as a whole, with gains offsetting losses before performance rewards are crystallised? The difference is more than technical; it goes to the heart of whether LPs feel their capital is treated fairly.
Equalisation raises similar questions. Early investors often shoulder more risk, committing to a “blind pool” before investments are secured. Later investors may benefit from greater visibility. Without careful structuring, the cost of that timing can be borne unevenly, undermining the perception of fairness across LPs.
In Japan, standard contracts often lack some of the equalisation mechanisms seen in global markets. But international investors increasingly expect these protections as table stakes.
For GPs, the lesson is clear. Beyond strong returns, investor confidence depends on transparency, alignment, and fairness. These issues are not secondary: they are central to fundraising success.
At Langham Hall, we help managers design and operate structures that build lasting trust between investors and managers.
Raising Capital in Europe: Q&A with Atlantic-Pacific Capital
Europe’s growing role for US managers
For many US fund managers, Europe is shifting from a secondary consideration to a strategic priority. Strong institutional demand, a stable regulatory environment and a track record of significant commitments make the region an increasingly important source of capital.
At Langham Hall, we have seen this first-hand. The number of non-EU funds we service raising capital under National Private Placement Regimes (NPPR), one of the key routes into Europe, has risen by 250% since 2020, with total AUM increasing from €123 billion to €499 billion*. For scaled, well-positioned managers, expansion into Europe is becoming a logical next step: opportunity-driven, not defensive, and a way to diversify LP bases and deepen institutional access.
To explore what it takes to succeed, we spoke with Alexandra Cromer, Partner at Atlantic-Pacific Capital (APC), who shares her perspective on European investor expectations, regulatory pathways and the practical steps US sponsors can take to build a strong market presence.
Q: Firstly, can you tell us a little more about your experience raising capital in Europe?
Alexandra Cromer (AC): As a global organisation with thirty years of capital raising experience, Atlantic-Pacific Capital considers Europe a key fundraising market for our clients. The US remains the largest market for us; however, with established distribution capabilities on the ground in Europe, we raise meaningful capital each year from EU investors (around a third), with commitments also secured from LPs in the Middle East and Asia.
Part of our role as an advisor is to assist GPs with building a diversified investor base that can be supportive across multiple funds. Part of this process involves educating clients on how to access European capital. Engaging with an agent who understands the nuances of marketing in Europe and has deep relationships with institutional investors across the various countries is vital.
We take a very customised approach to each fundraise, spending time with our GPs before formally launching to develop the right “go-to-market” strategy. Our objective is to ensure our capital raises are efficient and tailored to the ambitions of the client; this requires preparation.
For US managers, whether first-time or established, seeking to raise capital in Europe, determining where we believe there will be interest is the first step in the process. This helps refine our approach. Given there are significant costs associated with marketing in Europe, for many (first-time funds or even a later fund), availing the National Private Placement Regime (NPPR) makes sense especially if it is a more targeted outreach campaign. In addition to the costs being less onerous than the full AIFMD marketing passport, we have been successful raising capital from LPs in the Nordics, UK, or Switzerland – locations with less complex regulatory requirements – as these investors are often more receptive to earlier funds, especially high-pedigree spin-outs with track record attribution. For more established managers who may have spent some time building brand awareness in Europe, we may collectively decide AIFMD is the better route to maximise capital raising opportunities. A considered hosted premarketing campaign (especially for funds raising >$1bil) can assist with the decision between NPPR and Lux fund under AIFMD.
Q: How attractive do you really think the opportunity in Europe is for North American fund managers? In other words, is the juice really worth the squeeze?
AC: There are several reasons US GPs consider Europe when looking at other geographies to raise capital from – investor diversification is often a key objective. Embarking on the international fundraising campaign can offer a path to increasing their fund size. Others consider European investor support as validation of their firm or fund strategy. There are also GPs with a niche strategy that is well suited to the European market (e.g., energy transition, Article 8 / Article 9 funds).
Ticket sizes can vary in Europe, not just across geographies and types, but also for strategies. There are large institutions seeking to be meaningful partners writing EUR 75m+, supported by a significant constituent of LPs committing € 20-60m tickets which can materially impact fundraising momentum. There is less of a herd mentality in Europe than say Asia, although of course it is certainly helpful if there is European support for a manager, especially if they are like-minded investors, and/or are considered by the market to be a tier one LP.
There is generally strong appetite for high-quality US opportunities from European LPs. This is a sentiment we often see when speaking with top-tier lower- and mid-market PE GPs who consistently attract domestic US support. However, there is a plethora of service providers, such as Langham Hall, that can support managers with the on-going reporting obligations and administrative challenges. The regulatory landscape should not be the reason that US managers shy away from Europe. Working with an agent that can identify early on key European investors and provide the manager with a dedicated road map is essential, this makes the process more efficient, and ultimately fruitful.
It continues to be difficult to displace an incumbent manager if they have delivered, and allocations for new and existing relationships across both Europe and the US remains tight given the lack of distributions over the last few years. Securing capital is highly competitive, especially for new GPs, and we recommend remaining open to exploring options.
Q: What is the biggest difference that you see between North American and European LPs?
AC: Europe has long been leading the way in support for sustainable strategies and initiatives so expect to see highly established and rigorous Due Diligence processes from European investors, especially when it comes to ESG/sustainability credentials. This is much more than a simple tick-the-box exercise; full integration into the fund’s processes from origination through to exit is a must, and not just for infrastructure opportunities.
Traditionally, institutional investors in parts of Europe have been more conservative, with VC and growth generally a smaller allocation of portfolios versus US LPs. Some consider European LPs to have lower risk appetites with a focus on capital preservation, especially given their exposure to infrastructure; however, with recent changes to interest rates, this is shifting. With fixed income or debt offering a similar level of return to say core infrastructure with less perceived risk, there has been some movement up the risk spectrum. This, of course, comes with additional risk requiring investors to rethink how they evaluate managers and opportunities.
The US offers a depth of market and performance that has been superior to Europe. The US also offers investors a route to specialisation with far greater options available for backing a sector-specific fund, which has become increasingly of interest as a complement to diversified offerings. We continue to believe, despite some of the current uncertainty, the US will feature in LPs’ portfolios in a meaningful way. Some LPs have noted a material increase in the proportion invested in the US, up from 50% to 75/80%, some as high as 100% demonstrating how attractive they see the opportunity there. At the core, European investors are like all LPs, seeking top-tier managers with a compelling strategy and consistently strong track record.
Q: How should North American sponsors prepare for marketing in Europe for the first time?
AC: Marketing in Europe is not something US sponsors should approach lightly. Preparation is key. This includes finalising all aspects of the offering and developing the full suite of marketing materials. In a crowded marketplace, the ability to be proactive and responsive helps to keep the investors’ attention.
We always advise starting the process early and encourage GPs to utilise pre-marketing. It is helpful to commence conversations with European LPs before fundraising as it can take time to build relationships and get onto LPs’ radar - it is easier to build a relationship when not asking for capital! It is also worthwhile making a trip or two to Europe during the off-season. When part of a well-choreographed marketing campaign, conferences can be additive, helping to increase market awareness, especially for less established GPs with more focussed strategies.
It is also important to ensure that anything relating to ESG/SFDR has been properly considered and there is a clear plan for implementation; it cannot be viewed by LPs as an afterthought for the GP.
Ultimately, it is a competitive market and LPs, by and large, hold all the cards; it is important to know your peers and be able to articulate succinctly your key points of differentiation.
Q: Finally, what is the one piece of advice you would give to a sponsor that is looking to market in the EU for the first time?
AC: Be prepared, be realistic and be memorable (for the right reasons!).
Supporting your European fundraising journey
At Langham Hall, we have guided more than 200 non-EU managers across private equity, credit and infrastructure through their European fundraising journeys. From navigating NPPR to setting up AIFMD structures, our team helps managers make informed decisions and move forward with confidence.
Learn more about raising capital in Europe and the different paths available from NPPR to AIFMD.
*According to Langham Hall’s own regulatory filing data (annex IV): 2019-2024.
Join our newsletter
By subscribing you agree with our Privacy Policy