LATEST INSIGHTS
Tasman Capital Partners Fund IV reaches first close and completes initial investments
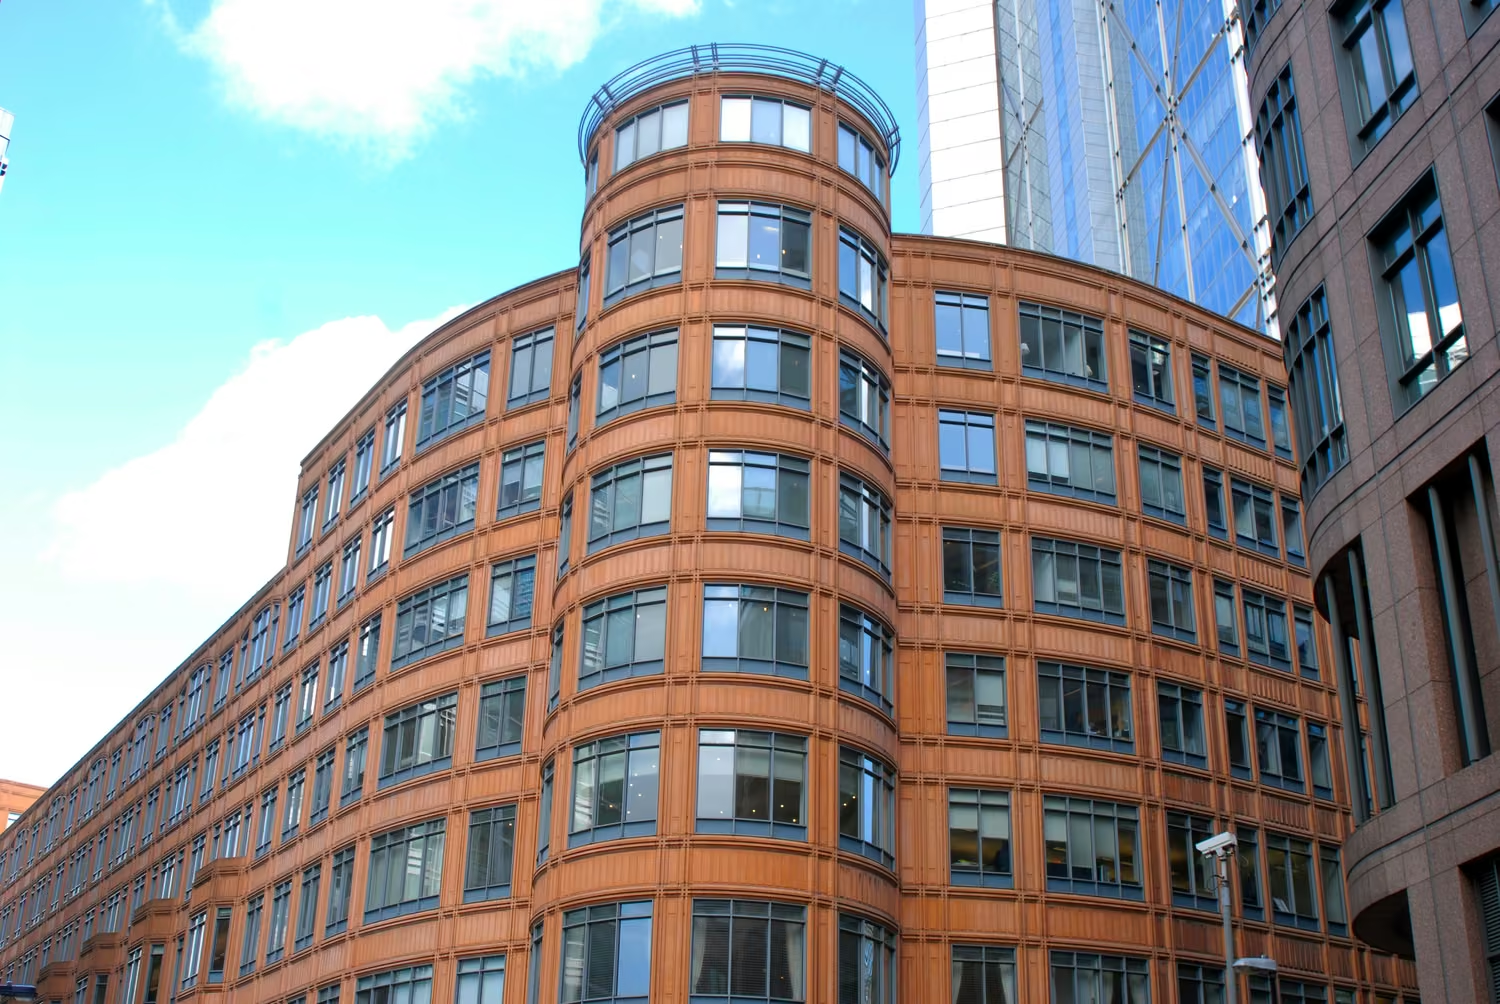
Langham Hall relocates London headquarters to Broadwalk House
Langham Hall has relocated its London headquarters to Broadwalk House, marking a significant milestone for the firm as it continues to scale its UK and international platform.
The move brings Langham Hall’s London team into a newly refurbished 20,335 sq ft office close to Liverpool Street, placing the firm at the heart of the City’s professional services district. The relocation provides capacity to support the firm’s growing London workforce of around 250 professionals, alongside enhanced space for collaboration, training and client engagement. Langham Hall has taken two floors at Broadwalk House, which is owned by British Land.
London remains a core market for Langham Hall, supporting private equity, real estate, infrastructure and credit fund managers with fund administration, AIFMD and depositary services. The move reinforces the firm’s client-facing presence, close to fund managers, advisers and the wider funds ecosystem.
Richard James, Head of Europe commented, “The move to Broadwalk House is an important step for our London business. It reflects both the scale we have reached and our long-term commitment to London as a global centre. The new office gives us the space and flexibility to support our people, work closely with clients and continue investing in the infrastructure that underpins high-quality delivery.”
Rob Short, Managing Partner commented, “London is where Langham Hall began and, as we have expanded internationally, it has remained an important location for European and increasingly US clients. We have applied the same principle globally, building teams close to our clients rather than relying on overseas outsourcing.”

Managing Partner's Update 2026
As we begin 2026, I would like to extend my best wishes for a happy and successful year ahead. I also want to share an update on Langham Hall and our expectations for the year to come.
As private markets continue to adjust to the new normal, there are early signs of stabilisation. Fundraising remains selective and exit activity uneven, but high-quality managers are returning to the market and we are seeing an abundance of new firms and spin-outs. In what is often described as a barbell environment, investors are showing the strongest conviction towards either clearly differentiated specialist strategies or scaled platforms, and selectivity has increased across the board.
We expect 2026 to bring a gradual improvement in liquidity and a more constructive fundraising backdrop, supported by continued secondary activity and a steady reopening of M&A. At the same time, expectations on transparency, governance and reporting continue to rise. Managers and investors increasingly want timely, decision-useful information, and greater confidence in the data behind it.
Langham Hall now has 900 people across Europe, Asia and the US and remains owned exclusively by management. This ownership structure underpins our priorities for 2026, which centre on client leadership, technical excellence and continued investment in our teams.
We will also continue to develop Wolfram and our computable data strategy, with a practical focus on improving data quality, reporting efficiency and the accessibility of client information. Across our offices, we remain focused on delivering joined-up support for managers and investors, combining local expertise with the depth of a global platform.
We have also continued to invest in leadership and in the foundations of our professional services. In 2026, Richard James will continue as Head of UK and will also take on the role of Head of Europe. This will strengthen our European platform and provide additional depth and support to jurisdictional leadership.
I would like to express my sincere gratitude to our clients and advisers for your continued trust and support.
Best wishes,
Rob Short
Managing Partner

Cayman update: PPoC residency and CIMA survey
As we begin 2026, we are writing to highlight two Cayman regulatory updates:
• Principal Point of Contact (PPoC) residency requirement
• Cayman Islands Monetary Authority (CIMA) Prudential Information Survey requirement
1. The PPoC residency requirement
What is changing
From 1 January 2026, a Cayman financial institution (FI) must appoint a PPoC who is resident in the Cayman Islands. Most Cayman private funds are FIs, so existing appointments should be reviewed.
Who is affected and when
• Existing FIs (registered on the DITC Portal on or before 31 December 2025): transition period to 31 January 2027 to move to a Cayman-based PPoC
• New FIs (registered since 1 January 2026): must appoint a Cayman-based PPoC on registration
How is this completed
• Appointment or change is filed via the DITC Portal
• The PPoC liaises with the Department for International Tax Cooperation (DITC), receives regulatory communications and, where required, adds a secondary user on the DITC Portal for FATCA and CRS
Why it matters
Failure to appoint a Cayman-based PPoC may attract an administrative penalty of up to KYD 10,000.
2. CIMA Prudential Information Survey (Registered Persons)
What is changing?
CIMA now requires Registered Persons (including SIBA investment advisers) to submit a Prudential Information Survey via the REEFS Portal. CIMA has issued a notice and a completion guide.
Deadline
For the 2025 calendar year, submission is due on or before 31 March 2026 via the REEFS Portal. Cayman registered office agents submit on your behalf.
How is this completed?
• Review CIMA’s notice and completion guide
• Prepare responses (we can provide a pre-filled template on request)
• Coordinate submission with your Cayman registered office agent via REEFS
Why it matters
Although the survey appears statistical, submission is a mandatory regulatory requirement for in-scope Registered Persons.
More information
• CIMA’s notice
• CIMA’s completion guide
How Langham Hall can help
Langham Hall works with Cayman partners to coordinate Cayman-based PPoC appointments and DITC filings. We also provide a pre-filled template to help Registered Persons complete the CIMA survey efficiently.
Get in touch
Please email aml.asia@langhamhall.com to discuss applicability to your structures or to request assistance with DITC or REEFS submissions.

Career reflections: Sophie Vallée-Berthold
Ten years of growth in compliance
Sophie Vallée-Berthold is Head of Compliance in Langham Hall Luxembourg and has spent the past ten years helping the office grow while strengthening its compliance framework. She reflects on how her role has evolved alongside increasing regulatory demands, particularly in areas such as AML and tax, and what she has learned about developing people through change.
Starting out in compliance
My career began in Luxembourg in 2008, when compliance was still emerging. With a law degree, I started as a Legal Advisor, which gave me my first insight into how closely regulation and business practice connect. My next role combined legal and compliance work, offering a clearer view of how the field was evolving and showing me how naturally the two areas fit together. Those early experiences are what drew me further into compliance.
I joined Langham Hall Luxembourg after my first parental leave as a part-time Compliance Officer, attracted by the flexibility and the chance to join a young business where compliance was becoming increasingly important. As the firm grew, so did the role, quickly moving to full time. It was a natural progression that allowed me to apply my legal background, deepen my expertise and grow with a firm still early in its development.
Early impressions and experiences at Langham Hall
In my first months, Langham Hall really felt like a start-up. There were only seven people in the Luxembourg office and everyone had to be ready to roll up their sleeves. I was learning a new role, a new company and an entirely new environment, all while taking on significant responsibility from the outset.
Despite the change in scale, one thing has stayed the same: the collaborative spirit that defined those early days. People share knowledge with each other and there is a sense of collective progress.
A key turning point was realising that, as I was developing, the firm was expanding just as quickly. Growing regulatory demands, especially around AML and tax, meant I was trusted with greater responsibility and soon began building my own team. Moving from doing everything myself to guiding others set the path toward a more strategic role focused on coordination, planning and people. The trust placed in me throughout has been central to my confidence and professional identity.
Growth and change
Starting in such a small team meant that learning happened in a very hands-on way. I benefitted directly from the experience and guidance of colleagues who were willing to take the time to teach and explain. It created a genuine apprenticeship environment and that way of working has remained central to Langham Hall’s culture.
Watching colleagues progress has also been a motivating part of the journey. Seeing people stay, work hard and develop into more senior roles reinforces the idea that growth here is real and achievable.
Personal reflections and proud moments
I am most proud of seeing the people I have trained grow into confident, trusted professionals. Contributing to the growth of the Luxembourg office, from a small start-up environment to a larger and more mature business, has also been a highlight, especially while maintaining strong compliance standards.
Over these ten years, I have learned that I can grow alongside significant change, that I enjoy developing others and that balancing technical work with genuine human connection is central to how I work.
I have realised that even in a serious field like compliance it is important to stay grounded, keep a sense of humour and not take oneself too seriously. Creating an open and relaxed atmosphere helps teams work better together.
Advice for new joiners
When I joined, curiosity was essential because we had to deal with everything ourselves. Even though we are now a much larger and more structured organisation, that early start-up mentality remains valuable. Do not wait for all the answers. Look around, ask questions and learn from the people around you. Collaboration is always there, but personal initiative is one of the strongest drivers of learning.
Advice for future compliance professionals
For anyone starting a career in compliance or finance, be ready for constant change. Regulations evolve and so do the businesses you support, so staying close to the detail and keeping your judgement sharp will help you stay one step ahead.

What makes a great accountant at Langham Hall Jersey
Great fund administration depends on strong fund accounting: disciplined processes, sound judgement and people who stay calm under pressure. We spoke with James Bruno, Senior HR Administrator in Jersey, about what “great” looks like and how we support long-term progression.
In fund administration, the technical work matters, but so does how people work. The best fund accountants combine analytical rigour with calm judgement, follow process with discipline, and keep learning as standards evolve.
At Langham Hall Jersey, we look for people who can handle complexity with care, build trust through accuracy, and develop quickly through structured support.
Q: What do you look for in a great fund accountant?
We look for people who combine technical rigour with good judgement. On the technical side, that means an analytical mindset, the ability to interpret complex data and spot patterns and a process-oriented approach to delivery. It also means being technically sound, with a strong grasp of accounting principles, systems and financial instruments.
Culturally, it matters just as much that someone is calm and composed, ethical and transparent and committed to continuous learning. The work evolves, so the best people stay curious and adapt as industry standards change.
Q: Why do these traits matter in fund administration?
Because clients rely on numbers they can trust, delivered on time. Strong fund accounting underpins accurate NAVs, predictable closes and clear reporting. When the operating rhythm is consistent, it reduces friction at month-end and quarter-end and helps teams spot issues earlier, before they become time-consuming fixes.
Q: What does process oriented look like day to day?
It means working in a structured way: understanding the close timetable, keeping documentation clean, following controls and making sure work is repeatable. It also means communicating early when something does not look right, so issues are resolved before they add pressure later in the close. Ultimately, it is about delivering accurate outputs on time in a way clients can rely on.
Q: What does progression look like in Jersey?
We take long-term development seriously. Langham Hall follows an apprenticeship model to support career progression, with study support available for colleagues pursuing ACCA qualifications and structured routes to grow from fund accountant roles into senior fund accountant, manager and beyond. Mentorship from senior colleagues is an important part of that journey.
Q: What makes someone progress quickly?
The people who progress fastest tend to take ownership of their development. They ask for feedback, seek out learning opportunities and stay proactive as the work becomes more complex. That mindset, combined with strong attention to detail, is often what accelerates growth.
Q: What should candidates do if they are interested in joining?
If you are looking for a place where standards are high, development is supported and progression is clear, we would welcome a conversation. Explore opportunities in Jersey or get in touch with our team to learn more.
Explore current opportunities in Jersey and across our global offices.

Emerging Managers: the operational transition from deal-by-deal to Fund I
Many US spinouts are taking longer to raise a traditional blind-pool fund and are building track record one asset at a time. That can open doors with sophisticated LPs, but it also exposes a recurring weakness: operating models engineered for single deals rarely carry cleanly into a fund. The transition from bespoke deal vehicles to a scalable, fund-grade structure is where most platforms lose momentum. The result is friction at precisely the wrong moment: extra diligence, timetable drift, re-papered terms and momentum lost before first close.
Why this matters now
Deal-by-deal capital has moved from niche to mainstream. Institutional LP backing for this model has deepened, signalling that club-deal paths are now a mainstream on-ramp to Fund I. Earlier this year, Global Endowment Management closed over $450m for an inaugural fund and affiliated vehicles dedicated to backing independent sponsors [1]. Industry trackers now estimate over 1,500 active independent sponsors in the US [2]. This volume means LPs now treat single-asset vehicles as de facto pilots for how an emerging manager will operate a commingled fund.
For many LPs, single-asset and club vehicles now serve as the first operational audit of a manager. At the same time, fundraising windows have lengthened and first-time closes have fallen, pushing more GPs to prove themselves transaction by transaction. In that environment, operating credibility, not just investment judgement, determines how fast a platform converts to Fund I.
What diligence is really testing
Most emerging managers assume historical performance is the main due diligence item. Increasingly it is not. LPs are underwriting the repeatability of the operating model at least as much as the deals themselves. In practice, CFOs are being asked to evidence three things:
- Economics and attribution are consistent and defensible across vehicles and will translate cleanly to Fund I terms
- Close and reporting cadence lands on time, quarter after quarter, with predictable capital call and distribution rhythms
- Controls, governance and data lineage hold under load as volume increases, including valuation discipline and audit readiness
That emphasis mirrors where regulators and operational due diligence (ODD) teams are looking: fees and expenses; custody and valuation; conflicts; and privacy and cyber hygiene, as highlighted in recent SEC examination priorities. ILPA templates remain the common language for reviewers. You do not need a big build to satisfy this; you do need clarity, cadence and documentation that stands up to challenge. LPs want evidence that the processes used today will survive scale, scrutiny and stress.
The operating model that must scale from single deals to a fund
Managers who convert quickly do not attempt a grand re-platform. They make a handful of early decisions and keep them consistent.
- Economics and attribution: Standardize fee bases, offsets, expense policy (including broken-deal treatment), carry and recycling. Calculate DPI/TVPI/IRR consistently (with a clear gross-to-net bridge), so performance carries credibly into a blind-pool raise. Inconsistency here is one of the fastest ways to trigger extended diligence.
- Close discipline: Publish a quarter-end calendar, fix responsibilities and service levels, and run a dry-run quarter before you raise. A week’s slippage each quarter becomes a pattern LPs remember.
- Data model and lineage: Lock a single investor identifier and a schema covering transactions, allocations, FX, fees and expenses end-to-end. If you can reconcile investment-level activity to investor-level reporting without manual stitching, you are already ahead at ODD. Most diligence failures trace back to manual reconciliations and orphaned data points.
- Valuation governance: Agree methodology, timetable and independence of challenge. Keep contemporaneous memos so audit becomes confirmation, not reconstruction.
- Treasury controls: Dual approvals, payment policies, segregation of duties and clear FX decision rights are table stakes and remove key-person concentration that ODD now flags quickly.
- Investor communications: Produce a standard reporting pack you can reproduce without rebuilding and keep Q&A logs and timelines consistent across vehicles. Rhythm and coherence matter.
Lean finance teams, scalable execution
Many first-time platforms run lean, whether led by a CFO, a Finance Director, a Controller, or an outsourced model. The objective is institutional discipline, not a specific organisation chart. Appoint a single accountable owner for close, cash and reporting. Extend capacity through an administrator for workflow, reconciliations, valuation support and required regulatory filings. Hold a short weekly operating meeting during raise periods that focuses on actions and blockers. This is how teams scale from single deals to Fund I without creating operational debt.
Where models typically break and how to avoid it
The common failure is not technology; it is architecture. One person “owns the spreadsheet”, logic lives in emails and each quarter becomes a bespoke project. The remedy is mundane but powerful: a shared data structure with access controls, a written expense policy, a repeatable reporting pack and a standing timetable that your administrator and audit firm work to. None of this is expensive; all of it is visible in diligence.
A second failure is ad hoc economics that cannot be reconciled into a commingled model. Standardize early so the Fund I story does not require footnotes. A third is quarter-end drift during a raise. Agree service levels with internal teams and providers, pre-book valuation timetables and test them in a dry-run quarter before you start marketing. Predictability beats perfection.
What LPs expect to see
Well run managers can show rather than tell. Close completion times versus calendar for the last four quarters. Adherence to reporting service levels and capital notice timetables. Low and declining error rates and aged reconciliation items. Valuation memos with dates and inputs. Clear evidence that track record and economics map cleanly to Fund I terms. This is the language of operational due diligence as we move into 2026. Data integrity, timetable discipline and audit readiness. Transparent inputs, defensible outputs and processes that do not depend on ‘heroics’ at quarter end.
The outcome
Deal-by-deal activity is now a mainstream on-ramp to Fund I. Teams that convert fastest treat early vehicles as fund-grade infrastructure, not exceptions. They keep economics consistent, close with discipline, maintain clean data lineage and run controls that stand up when tested. If you wish to avoid a costly reset later, pressure test the operating model you have today against three questions: can you close on time; can you defend every number; can the process scale without breaking quarter-end. If the answer to any of these is “no” the time to fix it is before you go to market.
Langham Hall supports emerging managers and established platforms alike, providing partner-led administration, reporting and governance that scale as firms grow. We help management teams design and run fund-grade controls, reporting and data infrastructure that travel cleanly into a commingled fund. If Fund I is on your agenda, please do get in touch.
[1] GEM Closes On Over $450 Million - April 2025
[2] A Lender’s Lens on the Independent Sponsor Market - H.I.G. Capital

British Virgin Islands (BVI) Approved Manager regime: a lighter-touch option for eligible private fund structures
For managers building or scaling offshore funds, structuring choices often come down to a familiar trade-off: regulatory credibility versus administrative complexity. One option that is still comparatively underused in Asia Pacific is the BVI Approved Manager regime, which can provide a lighter-touch approach for certain offshore investment managers and advisers, subject to meeting specific conditions.
What it is
The BVI Approved Manager regime is designed for certain offshore managers and advisers seeking a proportionate regulatory route. Where conditions are met, a BVI Approved Manager is exempt from the requirement to hold a full investment business licence and is subject to lighter ongoing regulatory obligations than a fully licensed model.
Where it can be used
A BVI Approved Manager may act as an investment manager or investment adviser to closed-ended funds established in the BVI or another recognised jurisdiction, including structures such as a Cayman GP/LP model.
Key conditions (in outline)
Whilst the detail needs to be confirmed on the facts and with offshore counsel, the key conditions are:
- Size threshold: for closed-ended funds, aggregate capital commitments are below US$1 billion
- Eligible fund type: the fund meets the BVI’s definition of either a Professional Fund or a Private Fund
For Professional Fund structures, the regime typically requires that:
- Fund interests are issued only to professional investors or similarly qualified investors (for funds in a recognised jurisdiction)
- The initial investment of each investor is not less than US$100,000 (with limited exemptions, including for certain team vehicles)
Practical points
Two practical considerations are worth flagging early:
- Economic substance: under most conditions BVI Approved Managers may fall outside the BVI economic substance regime, although this should be confirmed on the facts
- Ease of process: the application process is reported to be reasonably fast and straightforward
Why it matters
For managers building or scaling an offshore platform, the Approved Manager regime can be a useful additional option in the structuring toolkit, particularly where the goal is to reduce regulatory and operational burden whilst maintaining professional standards around governance and oversight.
If you would like to discuss whether the regime could be relevant for your platform, please do get in touch.
*This article is provided for general information only and does not constitute legal or tax advice.
Carbon reporting that turns data into action
We sat down with Richard James, Head of UK, to explore how better data drives better decisions. In partnership with Alectro, we now have clearer visibility of Scope 1–3 emissions across the group, helping us focus on the levers that matter most. The result: practical change and measurable progress, including a 10 per cent reduction in emissions per employee between 2023 and 2025.
Q1. Why does carbon reporting matter to Langham Hall?
It gives us clarity. With accurate Scope 1–3 data we can see the biggest levers and prioritise actions that reduce emissions and create value.
Q2. What has changed since partnering with Alectro?
We have end-to-end visibility through the Virtual Sustainability Officer platform and a simpler workflow for data collection. That has supported a 10 per cent reduction in emissions per employee between 2023 and 2025, driven by practical improvements across travel, procurement and resource use.
Q3. Where does the data make the biggest difference day to day?
In decision-making. Teams can compare options with a common dataset and select the route that delivers the best outcome for the environment and the business.
Q4. What sets Alectro apart in your view?
Integration and interpretation. The platform fits how we work and the team helps translate complex data into actionable insight. That combination accelerates progress.
Q5. What is next for our ESG programme?
Continual improvement. We will expand data coverage, refine reporting and focus on initiatives with measurable impact. The aim is simple: keep turning insight into action.
Fair value, not fairy tales: how investors test your numbers
Fair value is not an abstract accounting exercise. It is a practical tool for investor protection and decision-making. In Asia today, with fundraising cycles lengthening and audits tightening, LPs are testing whether managers’ numbers stand up to scrutiny.
For asset owners, from pensions and insurers to banks and corporates, the question is simple: does today’s valuation help me manage risk, allocate capital and communicate clearly?
For managers, this requires moving beyond a “manager’s mark” mindset. Investors increasingly expect valuation processes that minimise discretion, separate duties between deal teams and valuation oversight, and evidence external challenge where appropriate. Advisory boards are asking sharper questions. Many global LPs favour independent inputs or third-party reviews to remove conflicts and drive consistency across portfolios.
Why now in Asia? Fundraising cycles have lengthened, audits are probing methodology and data provenance, and cross-border investors compare outcomes across jurisdictions. Japan’s market is also shifting: international allocators increasingly expect fair value as standard, not a nice-to-have. In this context, the objective is alignment: a valuation approach that investors trust because it is explainable, repeatable and evidence-based.
A pragmatic framework helps:
- Governance: clear separation of origination and valuation oversight; documented challenge and sign-off
- Methodology: consistent techniques (market, income, cost) with rationale for selection and key assumptions
- Evidence: multiple sources, audit trails, and direct company data validated where possible
- Materiality and frequency: focus effort where it changes decisions; refresh in line with risk and liquidity
- Communication: translate methods and outcomes into investor-relevant insights (risk, runway, cash, progress to value-creation plan)
For GPs, fair value done well reduces friction in audits and LP conversations, shortens diligence cycles and strengthens credibility in a competitive fundraising environment. For LPs, it supports asset-liability management and comparability across managers.
At Langham Hall, we help managers design and operate valuation and reporting processes that meet international expectations while remaining practical for Asian portfolios.
Join our newsletter
By subscribing you agree with our Privacy Policy