LATEST INSIGHTS
Ben Thompson Spotlight: From Trainee to Assistant Manager
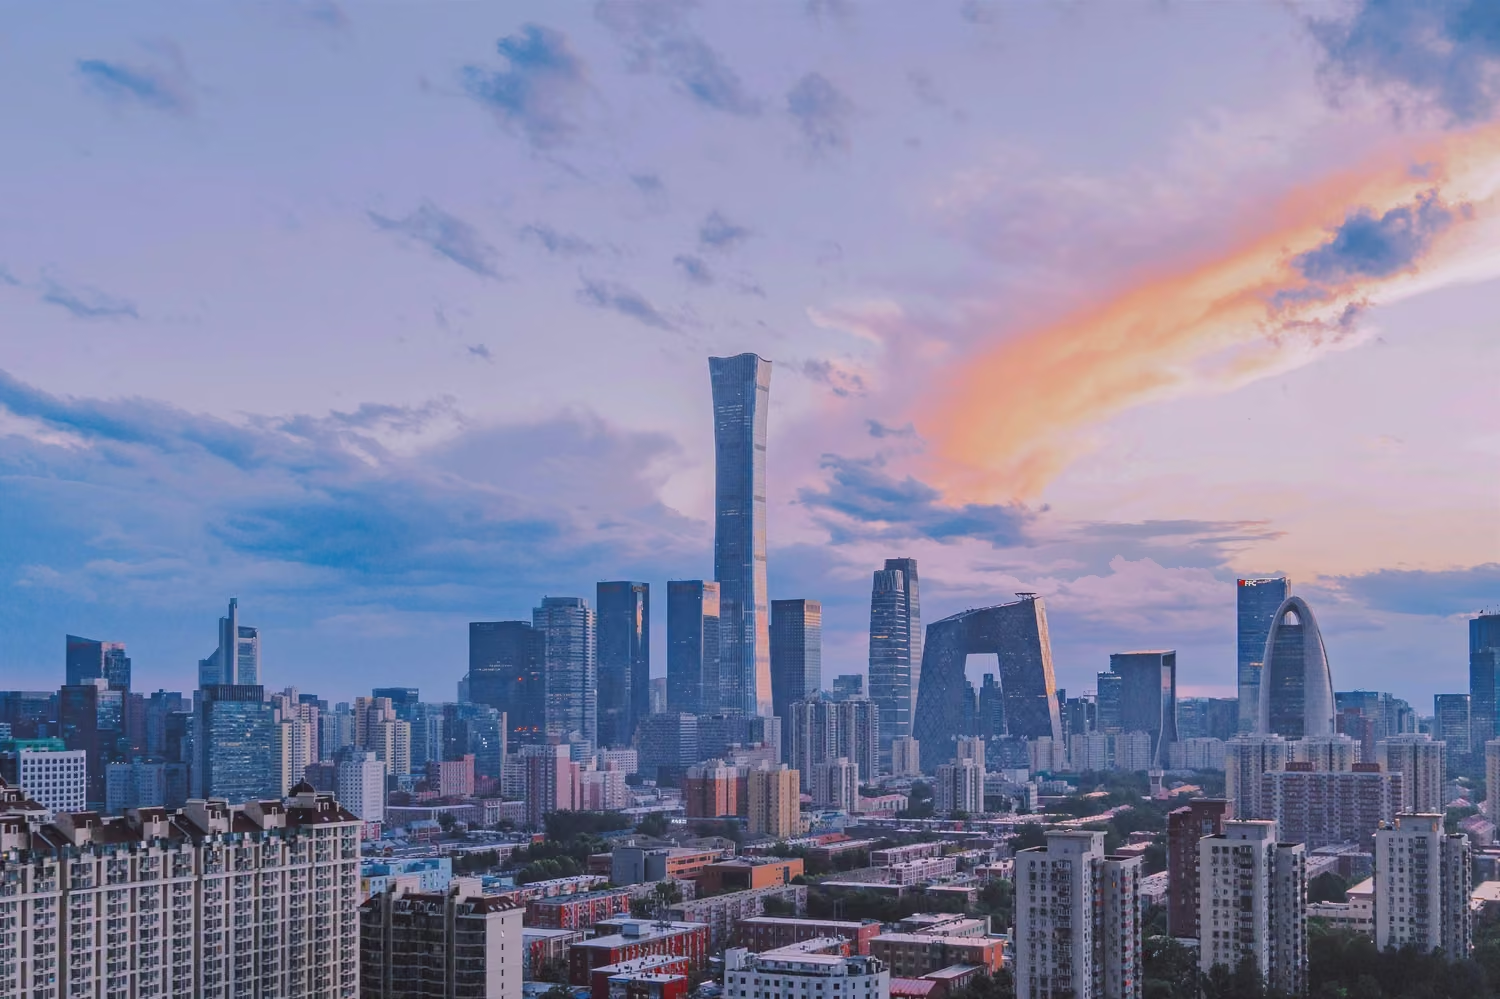
From Beijing: what client conversations suggest about fundraising, liquidity and AI
Client conversations in Beijing point to a market that is beginning to move again, though in a more selective and hesitant way than in earlier cycles. There are promising signs of successful fundraising activity.
Compared with recent years, new fund discussions are more active and a growing number of processes are progressing towards initial close. But this is not yet a broad-based rebound. LPs remain cautious, confidence takes longer to build, and decision timelines are extended. Capital is returning selectively, naturally with an initial focus on the more obvious and lesser-challenged opportunities in technology, AI and healthcare specialities.
Commitment sizes of new funds may be smaller than predecessor vintages
One consequence is that fund size matters more than it once did. In the current environment, smaller, venture-focused strategies are often an easier starting point for international investors reassessing the China market. Large buyout or flagship vehicles will certainly attract interest, but likely from a more selective group of re-up LPs who are now under-allocated to China in a world full of macro uncertainties and global “unknown unknowns”.
Shorter investment periods and more specificity on the initial pipeline can help managers re-establish a track record and build investor confidence before returning with an additional fundraise relatively soon.
Differing roles for domestic (RMB) and overseas (USD) fundraising
Another clear theme was the continued divergence between domestic (RMB) and overseas (USD) fundraising conditions. Both are challenging, but for different reasons.
It is interesting to draw a contrast between domestic fundraising in China and in Japan. In China, most domestic investors are ultimately local or central government institutions. Their requirements are only partly financial return, but more about stimulating investment or bringing business to certain industry sectors or regions. This is not necessarily easy for GPs to accomplish.
Japan, by contrast, has a very deep pool of independent central and regional financial institutions who invest directly for returns. A consequence is that whilst Japanese GPs may never need to look to overseas investors if their business ambitions can be accommodated domestically, Chinese GPs tend to see domestic fundraising as an interim approach until overseas investors can be tempted to return in volume.
Fundraising for China-focused USD funds is still challenging. Even so, the picture is not uniform. Interest is re-emerging among overseas investors, particularly in areas such as AI, robotics and related enabling technologies, where China’s structural strengths remain compelling.
AI and robotics interest remains strong
Those sectors featured prominently in discussions. AI and robotics continue to attract attention and, in some segments, deal activity is moving quickly. Even so, valuations remain materially more attractive than in the US.
Investor approaches to AI are becoming increasingly differentiated. Whilst some continue to focus on software and large model strategies, others are placing greater emphasis on connected sectors, with growing interest in hardware, infrastructure and AI enabled robotics, where competitive advantages may prove more durable over time. Rather than converging on a single dominant approach, this reflects an investment landscape in which capital is being deployed across a broader range of specialised AI related opportunities.
Recent global events have had an unexpected silver lining for China
Whilst global macro and geopolitical uncertainty continue to shape LP behaviour, discussions suggest that investors are increasingly adjusting to these conditions rather than stepping back entirely.
Recent events in the Middle East have been interpreted by some investors as a positive for China. China has a different energy policy from Europe and the US. From a market and political viewpoint, China may also be starting to command a stability premium. This is feeding through into fundraising dynamics, but of course global uncertainty is never good for fundraising.
What this means for GPs in China
For GPs in China, 2026 will be a year in which fundraising initiatives, even where ambitions have been scaled back from past cycles, will likely be rewarded with concrete results. There is a strong sense that market improvements are structurally very well supported.
If you would like to discuss any of these themes further, please do get in touch.
The rise of co-investments and SMAs
Why the Channel Islands are well positioned to support flexible private capital structures
Private markets continue to evolve as institutional investors seek greater control, transparency and efficiency in how capital is deployed. One result has been the growing use of co-investment vehicles and separately managed accounts (SMAs).
These structures are used by institutional investors, sovereign wealth funds, pension funds and family offices to gain greater visibility over individual transactions and, in some cases, improve fee efficiency and portfolio alignment.
As demand grows, jurisdictions able to provide regulatory certainty, structuring flexibility and experienced service providers have become increasingly relevant. The Channel Islands have long been used as a domicile for private capital structures and remain well placed to support them, with Guernsey continuing to play an important role within that landscape.
A structural shift in private markets
The growth of co-investments and SMAs reflects a broader shift in the relationship between fund managers and institutional investors. As allocations have grown and LP-GP relationships have matured, bespoke structures have become more commercially viable for a wider range of institutional investors.
Traditionally, investors committed capital to blind-pool funds where investment decisions were made by the general partner. While this model remains central to private markets, some investors now seek additional structures that offer greater transparency around individual transactions.
Co-investment arrangements allow limited partners to invest alongside a fund in specific deals, often on different fee terms from the main fund. This can increase exposure to particular investments and may affect overall fee outcomes.
Separately managed accounts take this further by giving investors a dedicated mandate. These mandates can be structured to reflect specific preferences around sector exposure, geography, asset class and risk profile.
For managers, co-investment capital can also support larger transactions and allow investors to increase their exposure to selected opportunities.
Why the Channel Islands are well positioned
The flexibility required to support co-investment vehicles and SMAs makes jurisdictional choice important. Structures may need to be established quickly, accommodate different investor requirements and operate alongside existing fund vehicles.
The Channel Islands have a long-established funds industry and are frequently used for private capital structures.
Their regulatory frameworks are overseen by the relevant regulators in each island and combine investor protection with regimes designed for investment funds.
The islands offer a range of legal structures, including limited partnerships, companies and unit trusts. These can be used to accommodate different investment strategies and investor arrangements.
They also have an established professional services sector supporting private capital managers.
The role of specialist administration
Co-investment programmes and SMAs can introduce additional operational complexity. Administrators may be required to support multiple vehicles, different investor groups and demanding transaction timelines alongside traditional fund structures.
Specialist administrators therefore play an important role in supporting these arrangements, particularly where managers operate multi-vehicle investment platforms.
Langham Hall provides administration services to private market funds and investment managers. The firm works with private equity, real estate and private debt structures, including co-investment vehicles and SMAs.
Looking ahead
As investors continue to seek tailored investment exposure alongside traditional fund commitments, jurisdictions that can support a range of structuring options are likely to remain relevant.
The Channel Islands’ legal frameworks, established funds industry and professional services ecosystem mean they are likely to remain important to these structures. As these models become more common, the ability to administer them with precision, responsiveness and technical depth will matter just as much as the jurisdiction in which they are established.
Langham Hall supports successful first close of Future Planet Capital’s British Co-Investment Fund
Langham Hall, a leading global provider of fund administration and AIFMD services, has supported Future Planet Capital on the successful first close of its latest venture capital fund, the British Co-Investment Fund (“BCF”).
BCF has been established to provide defined contribution (DC) pension investors with access to high growth British companies, broadening access to the asset class for pension schemes and aligning with the Mansion House Accord. The fund has been added to Mobius Life’s platform, supporting wider accessibility over time, and aims to direct up to £1bn of pension investment to the sector over the coming years.
Langham Hall is delivering fund accounting and administration services from its London office, providing operational support throughout the fund’s launch and first close.
Tom Pinnell, Head of Commercial, Europe at Langham Hall, commented: “Congratulations to the Future Planet Capital team on reaching the first close of this fund. This is an important milestone both for FPC, but also for the DC pension market which has faced numerous challenges to investing in private markets in recent years.”
Ed Phillips, Managing Director at Future Planet Capital, added: “Langham Hall has been a trusted partner from launch through to first close, delivering high-quality support with efficiency, expertise and clarity. Their seamless operations have allowed us to remain focused on launching this important product.”
Future Planet Capital was advised by Eversheds Sutherland.
Execution now carries more of the return
In 2021, market momentum often compensated for a lack of internal discipline; in the current climate, the market no longer offers that safety net. For much of the past decade, performance was helped by conditions that sat partly outside the portfolio company itself: debt was cheaper, multiples rose more readily and liquidity was easier to find. Successful returns now depend on operational value creation and long-term sustainability. Investors are no longer patient; they are asking harder questions about exactly when and how their capital will be returned. Gone are the easy days of money.
Bain’s 2026 Global Private Equity Report captures the shift in a single line: “12 is the new 5”. Deals that once required around 5% annual EBITDA growth to achieve target returns now require something closer to 10% to 12%. Bain also notes that distributions as a share of NAV have remained at around 14% for four consecutive years, while average holding periods at exit are now around seven years.
Collectively, the data is quite clear: returns now hinge on operational execution and investors expect precise justification for longer hold periods. This shift exposes laggards; while some firms built disciplined reporting early, others are only now forced to modernize.
Why the operating model now matters more
When leverage and multiple expansion contribute less, firms need a clearer view of performance, a firmer grip on what is driving it and a faster route from information to action. Bain underlines the point when it notes that the high prices paid for assets in 2021 and 2022 meant acceptable returns required unusually strong EBITDA growth.
The finance function does not set the investment thesis. But in a market where that thesis has to hold for seven years rather than five, the finance platform often determines whether problems are seen in time to act.
First signs of weakness
For CFOs, the strain rarely first appears in strategy. It appears in the record. Information arrives late or in inconsistent formats. Board packs take more iteration than they should. Investor questions trigger work that ought already to have been done. Exit preparation exposes gaps between historical records, reporting outputs and the assumptions behind them. What looked manageable in a quarterly cycle can become far more expensive when a buyer, lender or incoming investor wants the numbers tied back without delay and in one version.
The problem is not usually that the firm lacks data; it is that the numbers do not reconcile quickly enough or clearly enough for someone to act on them with confidence.
What this means for CFOs
For finance leaders, the problem is rarely the number itself. It is whether it arrives in time to be useful. That usually comes down to three things:
- Seeing underperformance soon enough to change the outcome
If the first clear picture arrives after quarter-end, the team is left explaining a problem rather than helping the business respond to it.
- Tracing performance without rebuilding the story each time
When the underlying record does not hold together, time goes into reconciliation rather than judgement.
- Returning cash without turning each distribution into a new operational exercise
Closing, investor reporting and distribution execution should support liquidity, not create delay around it.
Why liquidity has become an operating test
Investors are not simply watching unrealised value and waiting patiently for it to resolve. They are watching whether capital comes back, how clearly the path to realisation is explained and whether the platform appears capable of turning value into cash in a slower market. Bain’s data on subdued distributions and extended holding periods shows how much now rests on that ability. As the moniker goes, DPI is the new IRR.
LPs have watched it. They are no longer asking only what a portfolio is worth. They are also asking whether the firm running it knows how to get the money out. The seven-year hold is therefore not just a market fact. In some cases, it is also a sign that the platform was less ready for exit than the investment case assumed.
For those firms, the reporting process stops being an administrative matter. It becomes part of how the platform is judged.
Where Langham Hall sits
At Langham Hall, we help finance teams build the reporting rhythm, controls and underlying discipline that stand up when scrutiny increases. That matters not because process is virtuous in itself, but because firms with a steadier record can move faster when the window opens, answer questions more quickly and return cash with fewer surprises.
Private equity has always rewarded judgement. What changes in a market like this is that weak discipline stops being survivable.
From intern to perm: building a career in Luxembourg
Starting a career in the funds industry often comes with a steep learning curve. At Langham Hall, many of our colleagues begin their journey as interns or trainees, gaining early exposure to real client work while learning alongside experienced professionals.
We spoke with Yashna Rengha, Junior Legal and Transaction Services in our Luxembourg office, who joined as an intern and is now working in a permanent role. She shared what surprised her most about the transition, the challenges of her first months and the advice she would give to others starting out.
Q&A with Yashna Rengha, Junior Legal and Transaction Services
How soon did you begin working with clients and what was that experience like?
I was exposed to client-facing work very early on during my traineeship.
While this initially felt daunting, especially as it was my first experience in a corporate environment, I was supported by the right guidance from the team throughout the process.
I truly appreciated being trusted with that level of responsibility from the outset. It allowed me to better understand both the technical aspects of the work and the expectations of clients in a real-world context.
Over time, this early exposure helped me build confidence and develop the ability to engage with clients more independently.
What was the most significant learning curve during your first few months?
The steepest learning curve in my first months was adapting to a new legal and operational environment in the funds industry.
Coming from a litigation background, I had to quickly familiarise myself with Luxembourg-specific structures, internal processes and the practical application of corporate governance in a service-provider setting.
What helped me get through it was being proactive, asking questions, learning from colleagues and taking the time to understand not just the “what” but the “why” and the logic behind each task.
With the support of the team, I was able to gradually connect my existing legal knowledge to the operational realities of the role. This made the transition much smoother and ultimately strengthened my confidence in handling more responsibilities.
What advice would you give to someone starting their journey here as an intern?
My advice would be to stay curious and not be afraid to ask questions. Starting in a new environment can feel overwhelming, but taking initiative to understand how things work, both technically and operationally, makes a big difference.
Also, make the most of the exposure you are given and learn from the experience of your colleagues. Even small tasks are opportunities to learn and understand the bigger picture.
Most importantly, be open to feedback. It is one of the fastest ways to grow and build confidence.
At Langham Hall, many careers begin with early responsibility, practical learning and close collaboration with experienced colleagues. Yashna’s experience reflects the opportunities available to those starting out in the funds industry. To find out more about early careers at Langham Hall, visit our careers page.
Asia venture capital is becoming more selective, but opportunity remains strong
Takeaways from the HKVCA Venture Capital Forum
The discussions at the HKVCA Venture Capital Forum pointed to an Asian venture capital market that is becoming more selective, but no less relevant or dynamic. The mood suggested a market entering a more mature phase, with investor confidence beginning to recover and attention focused on the areas where long-term value is most likely to be created.
One of the clearest themes was that opportunity in Asia remains substantial, particularly in sectors such as AI, robotics, new energy and healthcare. At the same time, the way investors assess that opportunity is becoming more disciplined. The conversation is moving beyond broad enthusiasm and towards a sharper focus on execution, governance and realised outcomes. That does not signal retrenchment. It signals a market becoming more exacting about what quality looks like.
Selectivity is becoming more pronounced
This was particularly evident in the discussion around manager selection. LPs continue to see opportunities in Asia, but they are applying a more rigorous lens to track record, reputation and the clarity of a manager’s narrative. DPI is also receiving closer attention alongside IRR, reflecting a stronger focus on realised performance. For managers seeking to raise capital, the message is not discouraging, but clear: strong opportunities remain available to those who can demonstrate credible execution, transparent reporting and a well-developed plan for value creation and exit.
AI is moving from promise to practical application
Technology remained central to the discussion, though the emphasis has become more practical. AI continues to attract significant interest, but the most compelling opportunities appear to lie in businesses that can translate technical capability into genuine customer value. The wider application of AI into mid-market use cases was highlighted as especially promising, suggesting that the most durable opportunities may come not simply from technological novelty, but from thoughtful and commercially grounded deployment.
China and Southeast Asia remain central to the opportunity set
China also emerged as an area of continuing significance, particularly as founders increasingly build products with global markets in mind. Panel discussions pointed to growing competitiveness in AI, notable cost efficiency and strong momentum in consumer-led innovation. Although valuation froth remains a consideration in some areas, the broader direction of travel is encouraging. Companies that combine product strength with the ability to connect technology to real market demand may be especially well placed to build lasting advantage over the coming years.
Across Southeast Asia, the outlook was similarly constructive, although with a clear premium on execution. India, Indonesia and Vietnam were identified as particularly important markets, with attention centred on the teams most capable of combining local understanding with operational rigour. The implication is not that capital is absent, but that it is increasingly discerning. In that environment, execution capability becomes one of the strongest signals of quality.
Cross-border growth and corporate capital
Another important theme was the role of corporate capital and cross-border expansion. Corporates are expected to remain key strategic partners for start-ups, while Chinese companies are playing a growing role across Asia and beyond. For fund managers, this adds a further layer of opportunity, particularly where they can identify businesses with the potential to internationalise successfully or to form meaningful strategic partnerships beyond their home market.
What this means for general partners
Taken together, the forum suggested an ecosystem that is evolving in a healthy and increasingly sophisticated way. There is strong investor interest in innovation-led sectors, rising global appetite for Asian technology and a clear recognition that high-quality managers can still attract capital. The difference is that the market is rewarding discipline more explicitly than before.
For general partners, that is a constructive signal. The opportunity set remains broad, but success will increasingly favour those who can combine local insight, sector expertise and operational credibility with clear governance and a realistic path to liquidity. In a market that is growing up rather than slowing down, that is a promising position for well-prepared managers to be in.
Langham Hall supports first close of British Business Bank’s British Growth Partnership Fund I
We welcome today’s announcement from the British Business Bank on the successful first close of British Growth Partnership Fund I at £200 million.
The fund achieved a first close with commitments from Aegon UK, Cushon Master Trust, M&G and the British Business Bank. Its first investment will be £8 million into Wayve, the UK autonomous driving company.
The fund has been established to increase access to venture capital for UK defined contribution pension schemes, supporting greater participation in the asset class.
Langham Hall is supporting the fund from its London office, providing fund accounting and administration alongside AIFM and depositary services.
Read the full British Business Bank announcement here: Press release - 1 April, 2026 | British Business Bank
Rewiring fund administration: data without dead ends
Data used to be a by-product of reporting cycles. Today it is central to reporting, analysis and decision-making. Investors, lenders and fund managers expect faster answers, often within hours. Across the market, many teams are contending not just with an oversupply of data, but with data that is often poorly organised and poorly integrated, leaving them reliant on fragile workarounds. Wolfram exists to reverse that pattern.
Where standard tools fail
Generic platforms are built for standardisation. Funds are not standard. Divergent terms, secondaries and evolving structures expose their limits. Workarounds follow and control weakens. The pattern is familiar: significant effort in, limited flexibility out.
The root cause is architectural. If a system hard-codes processes and reports, anything outside the template becomes manual. Late valuation changes, bespoke waterfalls or lender requests trigger parallel spreadsheets that sit outside proper lineage. Confidence erodes, not because the team lacks discipline, but because the tool cannot adapt at the speed the business operates.
Computable, not merely programmable
Wolfram takes a different approach. We work from computable data, developed in collaboration with Wolfram Inc, the company behind the computable data paradigm. The model is built around one coherently structured source of truth, with every output generated as a view of it, so data can be interrogated as easily as it can be reported. Change a parameter, extend a structure or add a data point and the next report recomputes. No black box, no dead ends. Structure at source, flexibility in use. The benefit is practical, not cosmetic: late adjustments are absorbed without re-runs or shadow files.
This approach also removes a common false choice. You do not need to force your operating model into our software, nor rip out your processes to suit a vendor’s template. We fit the framework to the fund and return the data in formats stakeholders can use.
Provenance and model
The approach is deliberate. On one side, Langham Hall’s deep fund administration expertise: how funds are structured, how terms diverge, what CFOs and COOs need to run the business. On the other, Wolfram Inc’s strengths: computable data, symbolic computation and knowledge-based automation refined over decades in Mathematica, Stephen Wolfram’s flagship system for technical computing. The result is a core that is mathematically sound and extensible, fitted by our team to the specifics of each mandate. We tried other routes. Full outsourcing delivered scale without fit. Full in-house delivered fit without scale. This blended approach does both and adapts as requirements evolve.
Governance at speed
Velocity without loss of control is the test. With computable data, permissions, lineage and review sit alongside speed rather than behind it. Reviewers can interrogate inputs and logic. Changes are visible, auditable and contained within the same model. The outcome is less rework, fewer hand-offs and a cleaner path from booking to board pack.
Transparent by design
Examinability matters. Outputs are explainable and traceable back to source. Internal teams and external reviewers can follow the thread. The aim is not to impress with opacity but to build confidence through clarity.
From administration to advantage
The future is not a prettier quarter-end. It is decision-quality information available when it matters. With a computable core, managers can:
- See performance as a living picture, with outputs recalculated as assumptions change
- Run underwriting feedback loops by pushing deal-level updates once and propagating them through fund-level views without rebuilding models
- Answer lenders and LPs in the moment by interrogating one dataset, generating relevant views and keeping the logic intact
- Coordinate across jurisdictions using the same architecture while adapting outputs to local requirements without duplication
In short, data stops being a by-product of administration and becomes an operating advantage for investment decision-making.
Why others haven't followed
The constraint is not imagination. It is time horizon and execution. Several structural forces hold the market back:
- Legacy gravity: Vendors of older systems optimise for backwards compatibility and broad market appeal. Those incentives favour stability over change and make deep innovation hard to deliver
- Cosmetic over core: Many competitors are not led by owner-managers with the appetite for the hard, unglamorous work. The common shortcut is a better front end laid over a legacy core, which does little to improve control or flexibility
- Point solutions without a backbone: Newer entrants have cherry-picked elements like waterfall automation, but most are not end-to-end. Data still moves in and out manually, breaking lineage and slowing teams. Adoption remains low as a result
- In-house builds that stall: A few large GPs have invested heavily in internal systems. In practice these are often treated as back-office utilities and momentum fades once an initial version is live
- Moving frontier: Built with Wolfram Inc’s computable stack, we benefit from ongoing advances in symbolic computation and automation, so capability compounds rather than freezing after go-live
Success needs a different model: a long-term architecture, tight client-side understanding and the technical leadership to guide developers, backed by ownership willing to persist until the details work and an R&D partner committed to pushing the computable core forward.
What clients tell us
The themes are consistent:
- Time returned to the business. A debt manager asked for mid-quarter cash flow views. Because the underlying data already sat in Wolfram, the report was generated without extra team effort and the middle office adopted the approach
- Greater confidence at month-end. Finance leads report fewer last-minute workarounds and a more reliable review process because late changes recompute through the same model rather than spawning spreadsheets
- A clearer view of performance. Investors want to understand the shape of returns, not just receive a static table. The ability to interrogate a single dataset, drill down where needed and produce relevant views has been a clear step forward
- Data delivered in formats clients can use directly. We do not force clients into our portal. If they prefer to receive a computable file they can use directly, we provide exactly that, with the logic intact and fully visible to the client
In practice this feels simple. Update one item and on the next run everything that depends on it updates. Reviewers can interrogate both inputs and logic. Nothing disappears from view.
Beyond quarter-end
Treating data as a living system rather than a quarterly by-product changes what is possible. The same structured dataset can produce management information for the executive team, lender packs mid-period and investor reporting at period end without rework. Onboarding is faster because structure is captured at source rather than corrected later. This approach has proved effective across jurisdictions and has resonated with CFOs and COOs facing heavy information demands and underwhelming vendor systems.
The aim is straightforward. Use a rigorous, computable core; fit it precisely to each client’s funds; keep outputs examinable; and allow change without collateral cost. In a market long on data and short on confidence, the advantage lies in architecture, not in volume. That is what Wolfram is designed to provide: data without dead ends.

Langham Hall shortlisted for the Drawdown Awards 2026
Langham Hall has been shortlisted for the Drawdown Awards 2026 in the following categories:
• Fund Administration: $50-500bn (total global private equity AUA)
• Fund Accounting Technology
The judging panel will now review all shortlisted entries before selecting the winners, who will be announced at the ceremony on Tuesday 23 June.
Commenting on the shortlisting, Tom Pinnell, Head of Commercial, Europe, said:
“We are pleased to be recognised across multiple categories. Our partner-led approach, robust controls and open-architecture technology help set us apart in the market and we remain focused on delivering the high-quality service our clients expect from us.”
Join our newsletter
By subscribing you agree with our Privacy Policy